

What's Happening?
Intel's stock has experienced a substantial 149% increase over the past few years, reaching a current price of $86.96. Despite this strong performance, analysis suggests the stock may now be fully priced. This assessment is based on Discounted Cash Flow
(DCF) projections, which estimate Intel's intrinsic value to be modestly below its current share price. Analysts anticipate Intel's free cash flow to transition from current losses to positive territory within the next decade, with annual cash generation projected to reach billions of dollars by 2030 and beyond. These projections are linked to Intel's significant investments in artificial intelligence (AI) infrastructure and foundry buildout, which are currently drawing on fresh equity and debt. The market's comfort in valuing the stock ahead of what current cash flows alone might justify is partly attributed to recent upgrades and AI-driven excitement.
Why It's Important?
The valuation of Intel's stock has significant implications for the U.S. technology and semiconductor industries. Intel's substantial investments in AI and foundry expansion are critical for maintaining its competitive edge and supporting the broader technological infrastructure in the U.S. If the stock is indeed fully priced, it suggests that investors have already factored in the anticipated future growth from these investments. This could influence investment strategies for other semiconductor companies and technology firms that are also heavily investing in AI. The shift from negative to positive free cash flow by 2030 is a crucial indicator of the company's long-term financial health and its ability to generate sustainable returns, impacting both institutional and individual investors. The pressure on Intel to deliver on its projected cash flow rebound is considerable, given the stock's recent strong performance and the high expectations embedded in its current valuation.
What's Next?
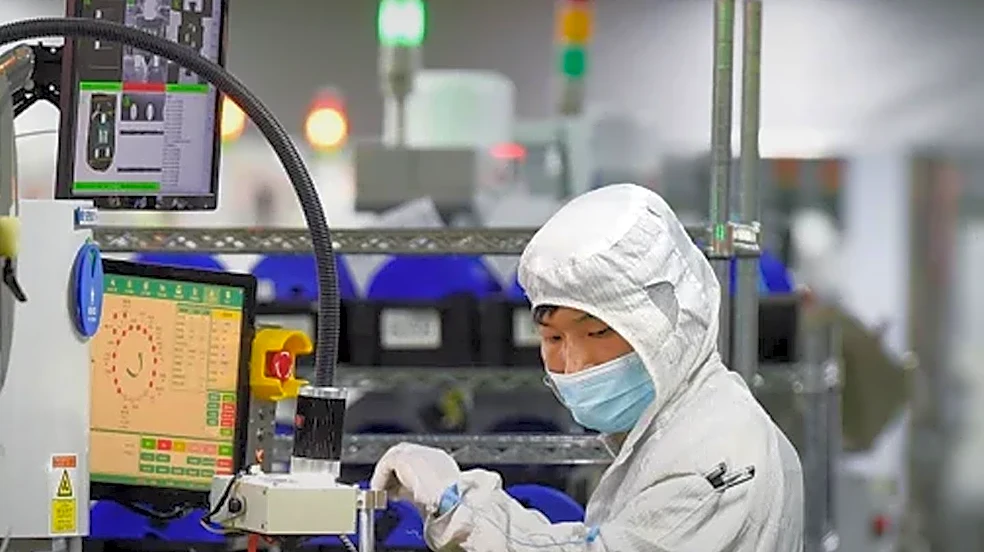
Intel's future performance will largely depend on its ability to successfully execute its aggressive investment strategies in AI and foundry buildout. Analysts are closely watching the company's progress in developing advanced process nodes, such as 18A and the planned 14A high-volume manufacturing by 2028. The success of these initiatives is crucial for transforming near-term capital outflows into long-term cash inflows. The market will also be observing how Intel navigates competition and potential manufacturing delays, which have impacted the company in the past. The ongoing debate among investors, with some seeing significant upside from AI and foundry spending and others expressing concerns about execution and competition, highlights the uncertainty surrounding Intel's future valuation. New information regarding Intel's business developments and financial performance will continue to shape these viewpoints and influence the stock's trajectory.
Beyond the Headlines
The situation with Intel's stock reflects a broader trend in the technology sector, where significant capital expenditure in emerging technologies like AI is driving market valuations. This trend raises questions about the sustainability of such valuations, especially when current cash flows do not yet support them. The reliance on future projections, particularly in rapidly evolving fields like AI, introduces a degree of speculative risk. The ethical implications of such investments include the potential for market bubbles if expectations are not met, and the impact on smaller competitors who may not have the capital to invest at the same scale. Furthermore, the strategic importance of Intel's foundry expansion extends beyond financial returns, as it plays a critical role in strengthening the U.S.'s domestic semiconductor manufacturing capabilities, which has national security and economic sovereignty implications.