

What's Happening?
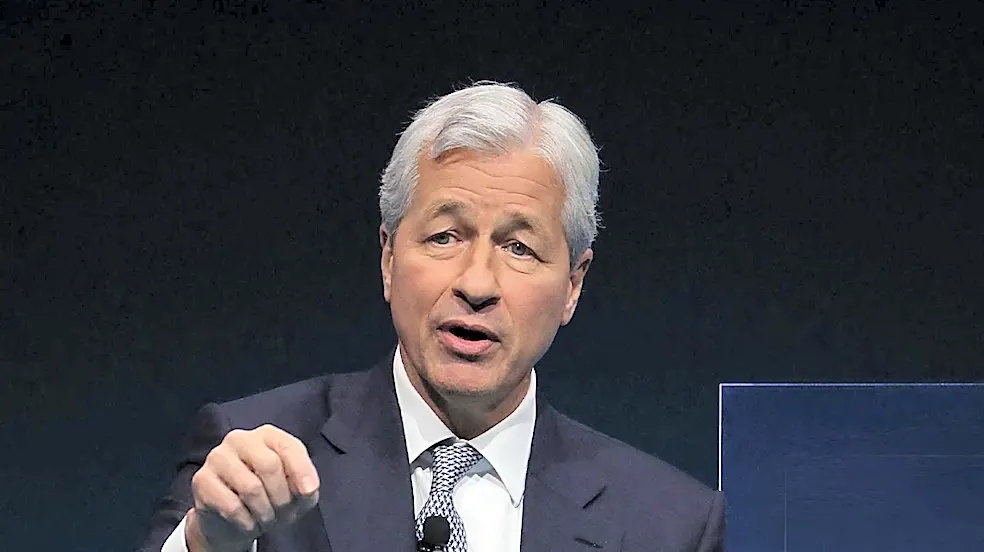
Jamie Dimon, Chairman and CEO of JPMorgan Chase, has issued a warning regarding the potential risks of artificial intelligence (AI) agents accessing customer bank accounts. During JPMorgan Chase’s October 13 earnings call, Dimon expressed concern about
the possibility of 'thousands' of rogue AI agents operating without proper oversight. These AI agents are designed to perform complex tasks, including moving money, if granted account access. JPMorgan Chase is currently restricting outside AI agents and is developing its own internal tools and protections to manage this emerging technology. The bank's CFO, Jeremy Barnum, highlighted that some services allow AI agents to move money by asking customers to share banking credentials, a practice JPMorgan opposes due to security concerns. Barnum cautioned that customers who provide their credentials could be held responsible for unauthorized actions taken by these agents.
Why It's Important?
This warning from a prominent financial leader like Jamie Dimon underscores a significant and evolving risk within the U.S. financial sector. The proliferation of AI agents capable of managing financial transactions introduces new vulnerabilities for both consumers and financial institutions. If rogue AI agents gain access to bank accounts, it could lead to widespread financial fraud, unauthorized transfers, and a loss of consumer trust in digital banking services. For banks, this presents a complex challenge in maintaining security protocols while also exploring the benefits of AI. The potential for 'liability transfer,' where customers might be held accountable for AI-initiated transactions, could erode consumer confidence in AI-driven financial tools and lead to increased disputes and legal challenges. Furthermore, the ability of AI agents to identify and move funds to higher-interest accounts could impact banks' profitability by shifting deposits away from lower-yield accounts within their own institutions.
What's Next?
In response to these concerns, JPMorgan Chase is actively developing its own secure AI tools, such as the Smart Cash tool, which is currently in a limited pilot phase. This tool aims to optimize customer interest earnings by moving money between accounts within the bank. Consumers are advised to review the access permissions of budgeting apps and payment tools, revoke access for unused services, and regularly monitor their bank statements for unfamiliar charges. Changing banking passwords may not be sufficient to disconnect these services, requiring users to check their bank's settings or seek assistance from their bank. The financial industry will likely see increased efforts to establish clear guidelines and regulations for AI agent access to financial data, focusing on security, liability, and consumer protection. This could involve collaborative efforts between financial institutions, technology providers, and regulatory bodies to create a safer digital banking environment.
Beyond the Headlines
The emergence of AI agents in personal finance raises profound ethical and legal questions about accountability and control. The concept of 'liability transfer' highlights a critical gap in current legal frameworks regarding AI-driven financial decisions. Who is ultimately responsible when an autonomous AI agent makes an error or acts maliciously? This issue could lead to complex legal battles and necessitate new legislation to define the roles and responsibilities of AI developers, financial institutions, and consumers. On an ethical level, the potential for AI to access and manage sensitive financial data without explicit, continuous human oversight challenges traditional notions of privacy and financial autonomy. The balance between convenience offered by AI and the imperative for security and control will be a central theme as this technology evolves, potentially reshaping how individuals interact with their finances and how financial institutions manage risk in an increasingly automated world.