

What's Happening?
Borr Drilling has signed definitive agreements to sell its 51% equity interest in Perfomex, its Mexican well services joint venture (JV), to its local partner. This transaction will result in Borr fully exiting its investment in Perfomex. The local partner will assume
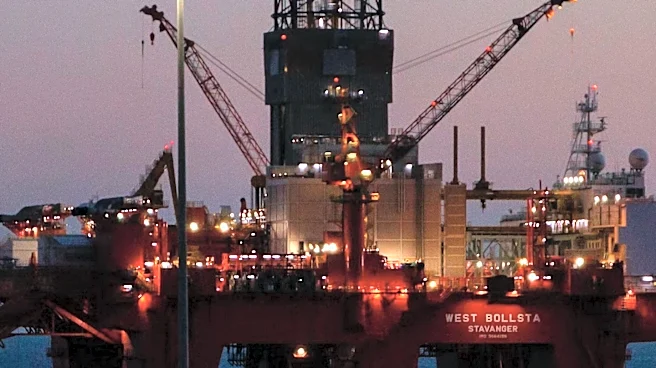
full ownership and operational control of the Galar, Gersemi, and Njord jack-up rigs, which are currently operating for PEMEX, the Mexican state-owned petroleum company. Despite the sale of its equity interest, Borr Drilling will retain ownership of the three rigs and will remain involved in the associated contracts through bareboat charter agreements. The commercial terms of these agreements are expected to remain largely unchanged from the existing arrangements. The Galar and Gersemi rigs have contracts extending until May 2030, while the Njord rig is contracted through April 2028, with options for extension. The sale price is based on the estimated net book value of Borr's equity interest in Perfomex as of July 31, 2026, with the transaction expected to close this month.
Why It's Important?
Borr Drilling's divestment of its majority stake in Perfomex to a Mexican partner signifies a strategic shift in its operational model within Mexico, moving from direct equity ownership in a JV to a bareboat charter arrangement for its rigs. This move could streamline Borr's financial structure and reduce its direct operational liabilities in the region, while still maintaining revenue streams from its rig assets. For the Mexican energy sector, this transaction empowers local partners with greater control over critical drilling operations for PEMEX, potentially fostering local expertise and capacity building. The long-term contracts for the rigs (up to 2030) ensure continued stability in drilling services for PEMEX, which is vital for Mexico's oil and gas production goals. This type of transaction can also reflect broader trends in international energy markets where foreign companies adjust their investment strategies to align with national content requirements or local partnership preferences, impacting the dynamics of energy services provision in key producing nations.
What's Next?
The transaction is scheduled for completion this month, pending customary closing conditions, and includes a transition period to support the transfer of operational duties to the local partner. Borr Drilling will continue to own the Galar, Gersemi, and Njord rigs and will maintain its involvement through bareboat charter agreements, ensuring continued revenue from these assets. This divestment follows Borr's recent expansion in the Mexican market through BC Ventures, a 50:50 JV with its Mexican well construction partner, which acquired five premium jack-up rigs for $287 million. Borr also finalized the acquisition of five premium jack-up rigs from Noble for $360 million in January 2026. These recent acquisitions indicate Borr's continued commitment to the jack-up rig market, albeit with a refined strategy in its Mexican operations. The market will observe how this new operational structure impacts Borr's financial performance and its strategic positioning in the global offshore drilling sector.
Beyond the Headlines
Borr Drilling's decision to sell its majority stake in Perfomex while retaining rig ownership and charter agreements illustrates a sophisticated approach to managing international investments and operational risks. This strategy allows Borr to de-risk its direct equity exposure in a foreign joint venture, potentially reducing political or regulatory uncertainties, while still benefiting from the demand for its high-value assets. It also highlights the growing trend of localization in the energy sector, where national oil companies and local partners seek greater control and ownership over critical infrastructure and services. This shift can lead to a more resilient local supply chain and enhanced national energy security. The long-term bareboat charter agreements underscore the continued demand for advanced drilling technology, ensuring that Borr's assets remain productive and profitable even without direct operational control. This model could become more prevalent as international energy companies navigate complex geopolitical and economic landscapes.