
What's Happening?
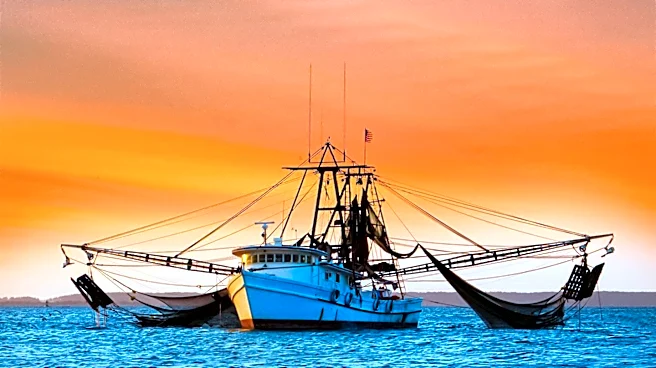
Indonesian shrimp exporter PT Bahari Makmur Sejati (BMS) is challenging allegations made by the American Shrimp Processors Association (ASPA) in an ongoing antidumping duty investigation on frozen warmwater shrimp from Indonesia. The dispute, currently
before the Court of International Trade, centers on BMS's methods for allocating raw shrimp costs among finished products. ASPA claims BMS used product size assumptions that artificially lowered shrimp costs, potentially understating dumping margins. BMS counters that ASPA's claim was not raised during the administrative proceeding before the Commerce Department and should be barred. Furthermore, BMS asserts its accounting methodology, which involves assigning standard costs and then adjusting them with actual production-cost variances, accurately reflects real production costs. The company highlights that the Commerce Department previously verified its cost-reporting methodology, finding it reasonable, supported by company records, and consistent with its production experience.
Why It's Important?
This case is important for U.S. industries as it directly impacts the competitive landscape for domestic shrimp processors. If ASPA's allegations are upheld, it could lead to higher antidumping duties on Indonesian shrimp, potentially increasing prices for U.S. consumers and benefiting domestic producers by reducing foreign competition. Conversely, if BMS successfully defends its accounting practices, it could maintain its market access and pricing structure in the U.S., continuing to offer competitive options to American buyers. The outcome will also set a precedent for how cost accounting methodologies are scrutinized in future antidumping investigations, influencing trade relations and import policies for other goods. The dispute underscores the complexities of international trade regulations and the rigorous standards foreign companies must meet to operate in the U.S. market, particularly concerning fair pricing and subsidy avoidance.
What's Next?
BMS has requested the Court of International Trade to either dismiss ASPA's arguments as untimely or reject them on their merits and uphold the Commerce Department's original determination. The court will review the arguments presented by both parties, including BMS's hypothetical examples and evidence of prior Commerce Department verification. A ruling from the court will determine the validity of BMS's cost accounting methods and could lead to a recalculation of antidumping duties, if any. The decision will have direct implications for the cost of Indonesian frozen warmwater shrimp imported into the U.S. and could influence future trade practices and investigations involving similar products. Stakeholders, including U.S. shrimp processors and importers, will closely monitor the court's decision for its impact on market dynamics and trade policy.
Beyond the Headlines
Beyond the immediate financial implications for the shrimp industry, this case highlights broader issues in international trade law regarding the interpretation and application of antidumping regulations. The debate over cost allocation methodologies touches upon the technical intricacies of global supply chains and the challenges of ensuring fair trade practices across different national accounting standards. It also underscores the ongoing tension between protecting domestic industries from unfair competition and maintaining open international markets. The legal doctrine of administrative exhaustion, central to BMS's defense, emphasizes the importance of raising all claims during the administrative phase of an investigation, a procedural aspect that can significantly influence the outcome of trade disputes. This case serves as a reminder of the detailed scrutiny and legal challenges that can arise in the enforcement of trade remedies.