

What's Happening?
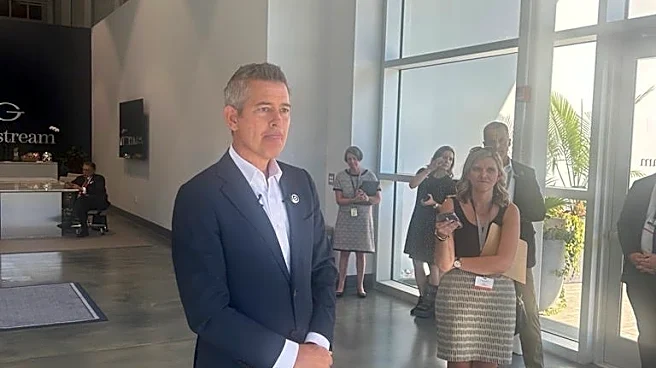
Senior leaders from Daimler Truck and Daimler Truck Financial Services recently held a discussion in Charlotte, North Carolina, addressing critical topics shaping the transportation industry. The panel included Eva Scherer, CFO of Daimler Truck Holding
AG, Stephan Unger, Chairman of Daimler Truck Financial Services, and Kevin Bangston, President and CEO of Daimler Truck Financial Services USA LLC, with Goetz Johanning moderating. Key insights emerged regarding the company's strategy for EPA 2027 compliant Detroit engines, emphasizing a fully compliant approach without relying on emissions credits. Scherer noted that the new engines will share approximately two-thirds of their parts with current models, aiming for reliability and offering about three percent better fuel economy. Despite the upcoming emissions changes, there hasn't been a pre-buy surge, indicating market uncertainty regarding the final 2027 regulations. The executives also acknowledged the recent freight recession's impact on Daimler's credit portfolio, with Bangston observing a recovery driven by capacity reduction rather than demand increase. The discussion highlighted the rising cost of money and its influence on truck purchasing decisions, with Daimler pushing for bundled financing, maintenance, and insurance packages.
Why It's Important?
The insights from Daimler's leadership are crucial for U.S. carriers of all sizes, from owner-operators to mega fleets, as they navigate significant industry shifts. The commitment to a fully EPA 2027 compliant engine provides clarity for equipment decisions, potentially reducing pressure for rushed purchases due to regulatory uncertainty. The observed freight recovery, though driven by capacity reduction, signals a potential stabilization for small and mid-sized carriers. However, the persistent volatility of diesel prices remains a significant threat, with carriers typically absorbing about 30% of fuel cost increases, which can severely impact thin margins. The rising cost of financing is reshaping how trucks are acquired, pushing carriers towards more comprehensive bundled service packages. This shift could offer more predictable monthly rates but also requires careful evaluation of ownership versus leasing models. For smaller carriers, understanding these financial dynamics and the implications of fuel costs is vital for maintaining profitability and making informed investment decisions in a challenging economic landscape.
What's Next?
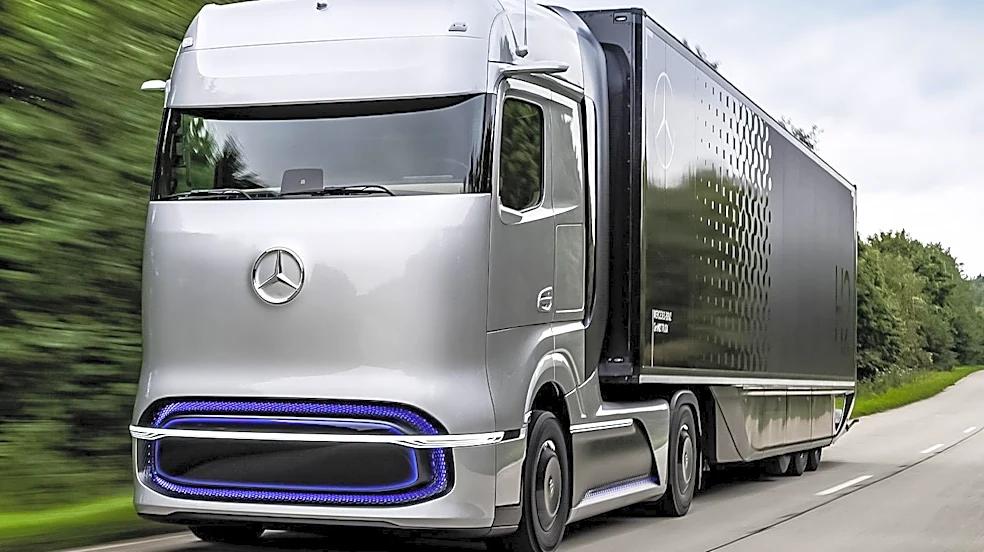
Daimler expects to deploy its first driverless truck on a route by the end of this year, with commercialization at scale targeted for 2028. This autonomous platform, an autonomy-ready Freightliner Cascadia with a virtual driver from Torc Robotics, will be modular, allowing compatibility with different virtual-driver companies. The business model for autonomous trucks will involve separate revenue streams: purchasing or financing the truck and chassis, with the virtual driver provided as a per-mile software-as-a-service layer. On the powertrain front, Daimler is pursuing a dual-track approach, focusing on diesel efficiency in North America with further improvements planned beyond 2030, while accelerating zero-emission truck development in Europe. The company's strategy is to let customer demand and market conditions dictate the pace of transition to electric vehicles in North America, rather than forcing it. Daimler also plans to support customers with depot and warehouse charging solutions and selective partnerships for charging infrastructure, rather than investing heavily in large-scale public charging networks.
Beyond the Headlines
The move towards autonomous trucking, with its modular design and software-as-a-service model, represents a fundamental shift in the economics of truck ownership and operation. This could lead to new business models, potentially reducing the need for human drivers on certain routes and altering labor market dynamics within the trucking industry. The dual-track powertrain strategy highlights the varying regulatory and market pressures between North America and Europe, suggesting a fragmented global transition to zero-emission vehicles. This could create challenges for international logistics and manufacturing, requiring adaptable supply chains and diverse technological investments. The emphasis on bundled financing and service packages indicates a broader trend towards integrated solutions in the commercial vehicle sector, where manufacturers are becoming more involved in the entire lifecycle of their products. This could offer greater predictability for carriers but also potentially reduce their flexibility in sourcing individual components or services, leading to a more consolidated and interdependent industry ecosystem.