
What's Happening?
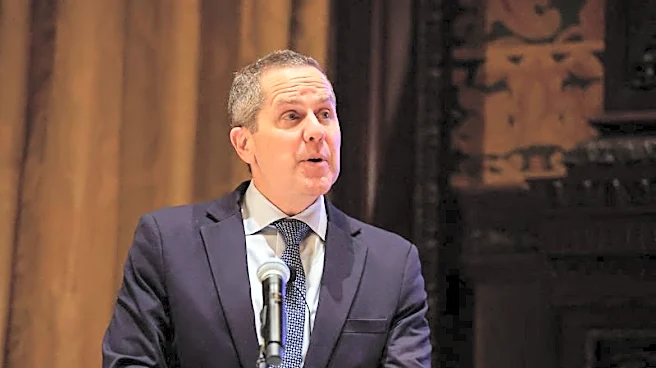
Federal Reserve Governor Michael S. Barr delivered a speech outlining the potential financial stability implications of artificial intelligence (AI), despite expressing optimism about its long-term promise.
Barr highlighted concerns from the Federal Reserve's latest Financial Stability Report (FSR), which focuses on the AI investment boom and the leverage in innovative debt structures financing this growth. The FSR notes that on-balance-sheet debt of the seven largest AI firms is projected to exceed $800 billion by year-end 2026. Additionally, off-balance-sheet liabilities, including long-term contracts and lease commitments, are estimated to surpass $3 trillion. Barr also pointed to 'circular financing' networks, where large AI firms invest in smaller ones that then use those funds to purchase services from the investors. He cautioned about the potential for a significant repricing of AI investments, which could lead to substantial losses and impact economic growth. The speech also addressed risks in wholesale securities trading, cybersecurity, and consumer finance, emphasizing the need for robust governance and oversight as AI integration expands.
Why It's Important?
The integration of AI into the financial system presents both opportunities and significant risks to U.S. financial stability. The rapid growth of debt financing AI infrastructure, particularly the substantial off-balance-sheet liabilities and circular financing, could amplify market shocks if AI investments are repriced. This could lead to widespread investment losses, reduced consumer and business spending, and a slowdown in economic output. In wholesale trading, AI could increase market concentration and information asymmetry, potentially leading to herding behavior, market manipulation, and systemic failures if similar AI models with flaws synchronize. For cybersecurity, AI enhances both offensive and defensive capabilities, but attackers only need to succeed once, potentially leaving defenders at a disadvantage. In consumer finance, AI raises concerns about investor protection, conflicts of interest, and fair lending, as AI systems may generate biased recommendations or make adverse decisions that are difficult to explain or dispute. These risks underscore the critical need for careful regulation and oversight to ensure AI's benefits do not undermine financial stability or consumer trust.
What's Next?
The Federal Reserve will continue to closely monitor the financial stability implications of AI, particularly the growth of advanced computing debt and complex financing structures. Policymakers and financial institutions are expected to engage in ongoing dialogue to develop strategies for managing AI-related risks. This includes focusing on model design, training data, testing, and deployment in financial markets to prevent unintended consequences like market herding or manipulation. Regulators will likely explore ways to enhance market surveillance using AI tools while also addressing the 'black box' nature of some AI algorithms. In cybersecurity, collaboration between the private sector and government will be crucial to ensure cyber defenses keep pace with AI-enabled threats. For consumer finance, institutions will need to invest in explainable AI techniques, continuous fairness monitoring, and accessible dispute mechanisms to ensure compliance with fair lending laws and protect investors. The development of technological innovations that ensure AI agents follow established rules and values will be critical as agentic commerce expands.
Beyond the Headlines
The rapid advancement and adoption of AI in the financial sector raise profound ethical and legal questions beyond immediate financial stability concerns. The potential for AI to exacerbate existing inequalities, particularly in consumer lending through biased algorithms, demands careful consideration of data ethics and algorithmic fairness. The 'black box' nature of some AI models challenges traditional notions of accountability and transparency, making it difficult to assign responsibility when AI systems make costly errors or engage in collusive behavior. The increasing autonomy of AI agents in financial transactions also introduces new legal complexities regarding consent, authentication, and liability. Furthermore, the concentration of AI development and deployment among a few large firms could lead to a significant shift in market power, potentially stifling competition and innovation. Addressing these deeper implications will require a multidisciplinary approach involving technologists, ethicists, legal experts, and policymakers to ensure that AI development aligns with societal values and promotes a fair, stable, and inclusive financial system.