



What's Happening?
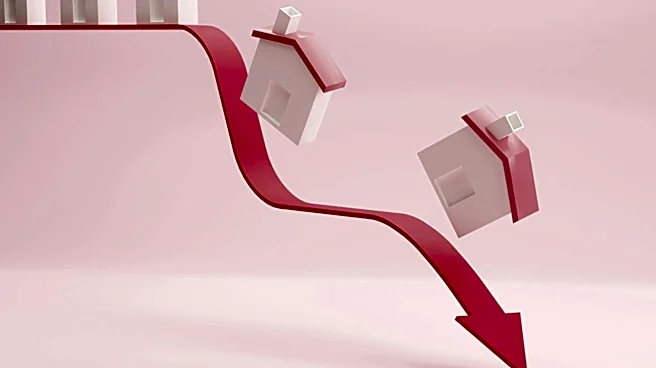
The U.S. housing market is currently in a 'rolling recession,' characterized by significantly reduced activity and low sales volumes, despite broader economic strength. Average 30-year mortgage rates have approximately doubled since late 2022 compared
to the previous decade, severely impacting buyer affordability. According to Realtor.com data, new U.S. home listings in October were down over 7% year-over-year and more than 16% lower than 2019 levels. Pending home sales are at their lowest since 2001, and housing starts are near a six-year low. While active inventory has risen by 7.5% from a year ago, this indicates a shift in seller behavior rather than a surge in demand, as sellers are less likely to delist properties compared to the previous year. The median list price in October was $415,000, a 2% decrease from a year ago but still nearly 34% higher than 2019, showing that home prices have not significantly fallen despite slow demand.
Why It's Important?
This protracted downturn in the U.S. housing market has substantial implications for the national economy and various stakeholders. High mortgage rates are pricing out many potential homebuyers, particularly low-to-moderate-income and first-time buyers, exacerbating affordability challenges. The 'lock-in' effect, where homeowners with lower mortgage rates are reluctant to sell, is contributing to the scarcity of new listings and stifling market dynamism. This situation creates a bottleneck, preventing trade-up homeowners from purchasing new homes and leaving builders with unsold inventory, while first-time buyers struggle to find affordable starter homes. The prolonged low turnover rate poses liquidity risks for mortgage servicers and lenders, who have seen minimal refinance production and face heightened pressure as elevated rates persist. Experts predict that a return to a well-functioning market could take up to five years, necessitating a shift in strategy for industry players.
What's Next?
The U.S. housing market is expected to continue facing challenges in the coming years, with a return to normal market conditions potentially taking up to five years. Lenders and servicers are advised to plan for a low-turnover baseline rather than anticipating a quick recovery. Fannie Mae has projected a significant downgrade in single-family refinance production for the next year, which has led Fitch Ratings to caution that some large nonbank mortgage companies may be uncomfortably exposed to further contraction in mortgage production. The current environment suggests that home sales will remain driven by necessity rather than choice, with high homeowner equity levels providing a price floor but not stimulating demand. Policy interventions or significant shifts in interest rates would be required to alter this trajectory, but no immediate changes are foreseen.
Beyond the Headlines
The 'rolling recession' in the housing sector highlights a fundamental shift in the American dream of homeownership. The confluence of high interest rates, elevated home prices, and stagnant wage growth for many has made homeownership increasingly unattainable for a significant portion of the population. This situation could lead to long-term societal changes, including a growing renter class and increased pressure on rental markets. The psychological impact on younger generations, who face unprecedented barriers to homeownership, could also be profound, affecting financial planning, family formation, and overall economic stability. The market's current state also underscores the interconnectedness of monetary policy, housing affordability, and broader economic well-being, demonstrating how sustained high interest rates can ripple through an entire sector with lasting consequences.