

What's Happening?
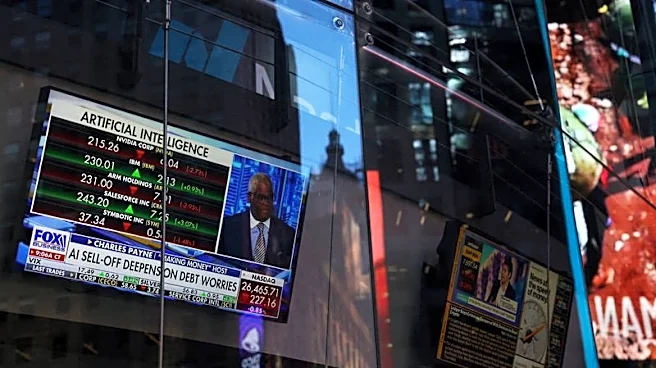
The recent sell-off in AI chip stocks is being framed by some analysts, such as Thierry Borgeat, as a forced hedge fund unwind rather than a verdict on the underlying demand for AI. Borgeat draws a comparison to 1998, suggesting that a broad deleveraging
by hedge funds, similar to the Long-Term Capital Management crisis, is causing the market pressure. He implies that such deleveraging events are often followed by a sharp recovery. Despite the plummeting AI semiconductor stocks, the AI boom itself is considered robust. Record weekly inflows into chip ETFs indicate that retail and institutional investors are treating the drawdown as an entry point, a strategy that has historically proven effective.
Why It's Important?
This interpretation of the AI chip sell-off is crucial for the U.S. financial markets and technology sector. If the downturn is primarily due to a hedge fund unwind rather than a fundamental weakening of AI demand, it suggests that the long-term growth prospects for U.S. AI companies remain strong. This perspective could prevent panic selling and encourage strategic investment, particularly given the historical precedent of a recovery after similar deleveraging events. For U.S. investors, understanding the distinction between market mechanics (like forced selling) and underlying economic fundamentals (like AI demand) is vital for making informed decisions and capitalizing on potential buying opportunities in a sector critical to national economic and technological leadership.
What's Next?
The market will be closely watching for signs that the hedge fund deleveraging has run its course, which, according to the 1998 analogy, could be followed by a "violent melt-up." Analysts will continue to monitor chip valuations, as some suggest they have only just reset from two to three times their median levels, indicating that the downside might not be entirely finished. The sustained inflows into chip ETFs suggest that many investors are already positioning themselves for a rebound. The key will be to differentiate between short-term market corrections driven by financial engineering and long-term shifts in technological demand. Companies in the AI chip sector will likely continue to emphasize their strong order backlogs and long-term growth projections to reassure investors.
Beyond the Headlines
The comparison to the 1998 Long-Term Capital Management crisis highlights the systemic risks that can arise from highly leveraged financial positions, even in seemingly robust markets. This event underscores the interconnectedness of financial markets and the real economy, where the actions of hedge funds can have significant, albeit temporary, impacts on critical technology sectors. It also raises questions about market transparency and the potential for cascading effects from deleveraging. For policymakers, such events might prompt discussions about regulatory oversight of hedge funds and market stability mechanisms. Culturally, it reinforces the narrative of market resilience and the potential for recovery after periods of intense volatility, shaping investor psychology and risk appetite in the long run.