
What's Happening?
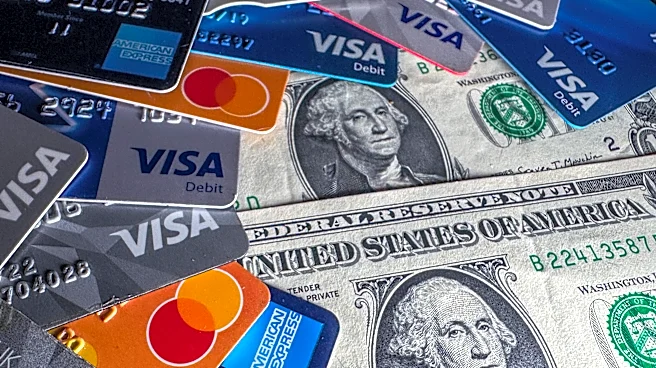
OpenAI has launched ChatGPT Wallet, a new payment feature designed to enable its artificial intelligence agents to complete online purchases for users. This initiative marks OpenAI's expansion into AI-powered shopping. The wallet was developed in collaboration
with major payment networks, including American Express, Mastercard, and Visa. The primary function of ChatGPT Wallet is to allow users to save their payment card details and authorize purchases without the need for repeated manual entry. Initially, this feature will be accessible to a select group of ChatGPT Pro subscribers within the United States, specifically through OpenAI’s Dots agent service. The system allows users to instruct their AI agents to locate products and finalize purchases. Before any transaction is processed, users are required to review the merchant, selected items, total cost, and payment card. Final approval is secured through a security check, such as Apple’s Face ID or a fingerprint scan. OpenAI has stated that the system utilizes payment tokens provided by card networks, ensuring that users' actual card details are not exposed to the AI agent or the merchant. Users will also maintain eligibility for card rewards and existing protections for qualifying payment disputes.
Why It's Important?
The introduction of ChatGPT Wallet by OpenAI signifies a notable advancement in the integration of artificial intelligence into daily consumer transactions within the U.S. This development could reshape e-commerce by streamlining the purchasing process, potentially increasing convenience for consumers and driving higher transaction volumes for online retailers. For U.S. industries, particularly retail and financial services, this could lead to new business models and partnerships, as companies adapt to AI-driven purchasing behaviors. Financial stakeholders, including American Express, Mastercard, and Visa, stand to benefit from increased transaction processing and deeper integration into emerging AI platforms. However, it also raises questions about data privacy and security, despite OpenAI's assurances of using payment tokens. The reliance on biometric security checks like Face ID or fingerprint scans highlights a growing trend towards advanced authentication methods in financial transactions. The limited rollout to ChatGPT Pro subscribers in the U.S. suggests a strategic, phased approach to market penetration, allowing OpenAI to refine the service and address potential challenges before a broader release. This move could also intensify competition among tech companies vying to dominate the AI-powered commerce space, influencing future innovation and investment in this sector.
What's Next?
Following its initial limited release to ChatGPT Pro subscribers in the United States, OpenAI will likely monitor user feedback and system performance to refine the ChatGPT Wallet feature. Future developments could include expanding availability to a wider user base and integrating with more merchants and payment options. OpenAI may also explore additional AI-powered shopping functionalities, such as personalized recommendations or automated price comparisons, to enhance the user experience. The collaboration with major payment networks suggests a long-term strategy to embed AI more deeply into the financial ecosystem, potentially leading to further partnerships with banks and other financial institutions. Regulatory bodies in the U.S. may also begin to scrutinize the implications of AI-driven purchasing, particularly concerning consumer protection, data privacy, and financial security, which could lead to new guidelines or regulations. The success of ChatGPT Wallet could encourage other AI developers to launch similar services, fostering a competitive landscape in AI-powered commerce and accelerating the adoption of AI in everyday transactions.
Beyond the Headlines
The launch of ChatGPT Wallet extends beyond mere transactional convenience, touching upon deeper ethical and societal implications. The increasing autonomy of AI agents in financial decisions, even with user approval, raises questions about the nature of consumer agency and responsibility. While the system requires user review and biometric authentication, the underlying AI's influence on product selection and purchasing patterns could subtly shift consumer behavior. There's a potential for algorithmic bias in product recommendations or pricing, which could disproportionately affect certain demographics or reinforce existing market inequalities. Furthermore, the reliance on payment tokens, while enhancing security, also centralizes more financial data within AI platforms, increasing the stakes for cybersecurity and data governance. The long-term shift could see AI agents becoming indispensable personal shoppers, blurring the lines between human decision-making and automated execution. This development also highlights the ongoing tension between innovation and regulation, as legal frameworks struggle to keep pace with rapidly evolving AI capabilities. The ethical considerations around AI's role in managing personal finances will likely become a more prominent discussion as these technologies become more pervasive.