
What's Happening?
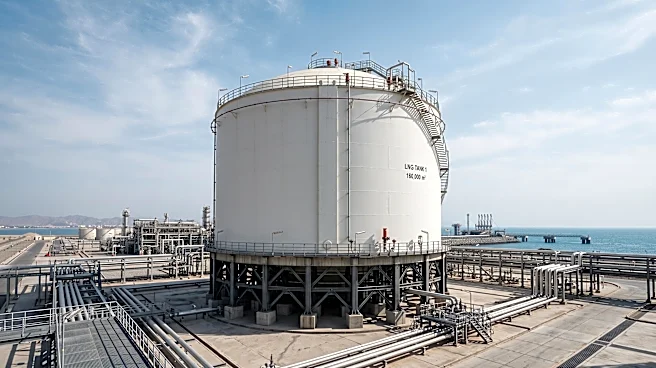
China's crude oil imports reached 9.88 million barrels per day (bpd) in October 2026, marking a 9.4% increase from the previous month and the highest level since March. This surge follows a period of reduced imports, which saw figures drop to a 10-year
low of 7.12 million bpd in June. Despite the monthly gain, overall imports for the first ten months of the year are down 15.1% compared to 2025. The country has been adjusting to reduced imports primarily by cutting exports of refined products. Imports from the Middle East have returned to pre-war levels, with 4.65 million bpd arriving in October. This increase in crude oil imports coincides with global manufacturers, including those in North America and Europe, accelerating precautionary stockpiling due to concerns about future inflation and supply disruptions, as reported by the GEP Global Supply Chain Volatility Index.
Why It's Important?
The recovery in China's crude oil imports is significant for global energy markets, as China is the world's largest crude importer. The increased demand from China, coupled with global stockpiling efforts by manufacturers, could exert upward pressure on international oil prices. This trend is particularly notable given the ongoing conflict in the Middle East, which has previously disrupted oil flows through the Strait of Hormuz. While China's refiners have the capacity to ramp up exports, their ability to do so is constrained by quotas, not market dynamics. The current high profit margins for refined fuels, such as diesel, suggest that increased exports would be highly profitable for Chinese refiners if restrictions were eased. The broader context of global manufacturers stockpiling to mitigate future inflation and shortages highlights a widespread concern about supply chain stability, which could lead to increased demand for various commodities, including oil, and potentially contribute to inflationary pressures.
What's Next?
The trajectory of China's crude oil imports and refined product exports will depend on several factors, including the duration and intensity of the Middle East conflict and China's domestic energy policies. If China's government relaxes export quotas for refined products, its refiners could significantly increase fuel exports, potentially impacting global fuel markets. The continued stockpiling by global manufacturers, including those in the U.S., suggests that demand for raw materials will remain robust in the short term. However, this inventory buildup could lead to a slowdown in purchasing demand once sufficient stock is accumulated, potentially creating a drag on manufacturing and the wider economy in 2027. The next release of the GEP Global Supply Chain Volatility Index in December 2026 will provide further insights into these trends.
Beyond the Headlines
The interplay between geopolitical events, national energy security strategies, and global manufacturing trends reveals a complex and interconnected economic landscape. China's strategic adjustments to its oil imports and refined product exports demonstrate a proactive approach to managing energy security amidst international instability. The global trend of precautionary stockpiling by manufacturers, driven by fears of inflation and supply disruptions, underscores a shift towards resilience in supply chains, potentially at the cost of increased working capital and future demand volatility. This could lead to a re-evaluation of just-in-time inventory models in favor of more robust, albeit more costly, supply chain strategies. The long-term implications include potential shifts in global trade patterns and increased focus on domestic production capabilities to reduce reliance on volatile international markets.