

What's Happening?
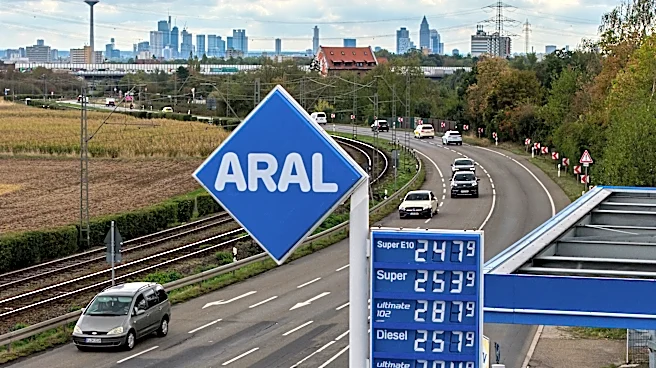
Goldman Sachs has issued a warning that the global fuel market is expected to remain tight through 2027, with diesel, gasoline, and jet fuel prices staying elevated. This projection is attributed to refinery closures outpacing new capacity, preventing
the market from absorbing a meaningful recovery in demand. Analyst Nikhil Bhandari suggests that refiners must maintain high margins to curb consumption and slow restocking, as demand otherwise risks outstripping supply. The bank's supply model indicates that outside of China, 300,000 barrels per day of new refining capacity in 2026 will be more than offset by 600,000 barrels per day of closures, leading to another year of net capacity losses globally. If demand increases by just 1% above 2025 levels and buyers only replace half of this year's inventory drawdown, refinery utilization would need to reach operationally unrealistic levels. This situation is further complicated by geopolitical factors and existing market disruptions.
Why It's Important?
This forecast has significant implications for the U.S. economy and various industries. Consumers, airlines, and trucking firms in the U.S. are likely to face a prolonged period of elevated fuel costs, contributing to inflationary pressures and potentially impacting operational expenses and consumer spending. Policymakers will also contend with inflation and supply risks. Conversely, U.S. refiners with reliable crude access, such as Marathon Petroleum and Valero, are positioned to benefit from unusually strong margins and cash flow. The sustained high prices are becoming a structural mechanism to balance an undersupplied system, rather than a temporary post-pandemic dislocation. The risk of global refined-product inventories falling to 2015-like levels by late 2026, and OECD stocks (including strategic reserves) dropping below historical minimums by mid-2027, highlights a potential energy security concern for the U.S. and its allies. The spillover of a diesel crisis into gasoline further underscores the broad impact on transportation and logistics sectors.
What's Next?
The U.S. market can anticipate continued high fuel prices, which will likely influence consumer behavior and corporate strategies across various sectors. Businesses heavily reliant on transportation, such as airlines and trucking companies, may need to implement long-term cost-mitigation strategies or pass increased costs onto consumers. Policymakers may face pressure to address inflationary concerns and explore options to bolster energy supply or manage demand. Investors will likely continue to favor refining companies with strong crude access, as they are expected to generate robust financial performance. The ongoing geopolitical landscape and potential for further supply disruptions will remain critical factors influencing market stability. The market will closely monitor inventory levels and refinery utilization rates, as these will be key indicators of the severity and duration of the tight fuel market.
Beyond the Headlines
The persistent tightness in the fuel market, as projected by Goldman Sachs, points to a deeper structural issue beyond short-term demand fluctuations. It suggests a fundamental imbalance between global refining capacity and energy consumption, potentially driven by underinvestment in new capacity and accelerated refinery closures. This situation could accelerate the transition towards alternative energy sources and electric vehicles in the U.S., as sustained high fossil fuel prices make these alternatives more economically attractive. Furthermore, the reliance on high prices to balance supply and demand raises ethical questions about energy accessibility and affordability, particularly for lower-income households and businesses. The potential for strategic reserves to fall below historical minimums also highlights a national security concern, emphasizing the need for robust energy policies and diversification strategies to mitigate future supply shocks and ensure economic stability.