

What's Happening?
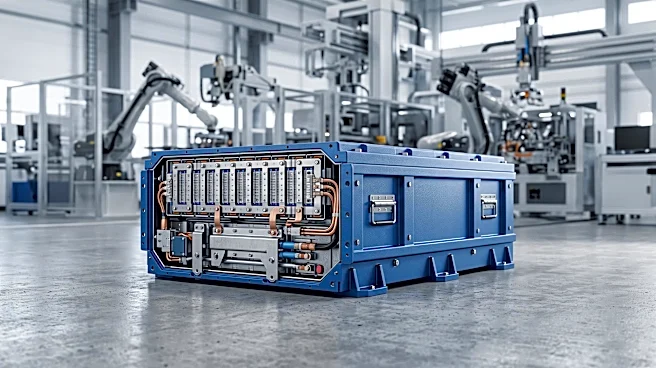
Chinese battery manufacturers, including CATL, EVE Energy, Gotion, and Sunwoda, reported significant revenue growth in their third-quarter earnings, with increases ranging from 45.78% to 63.08%. However, this revenue growth has not consistently translated
into higher profits. While EVE Energy saw an 86.11% jump in net income, CATL's growth slowed to 14.54%, Gotion's net income plunged by 66.48%, and Sunwoda dropped by 56.37%. This divergence is attributed to the substantial upfront investments required for their global expansion strategies, particularly in Europe. Companies are building new production facilities and joint ventures in countries like Germany, Hungary, Spain, Slovakia, and Morocco to meet growing international demand and navigate regulatory hurdles such as the EU's carbon footprint labeling and battery passport requirements. These overseas projects, while driving revenue, incur significant capital expenditures, depreciation, and financial costs during their construction and ramp-up phases, impacting current profitability.
Why It's Important?
The trend of Chinese battery manufacturers expanding their production capabilities into Europe signifies a major shift in the global battery supply chain. This move is crucial for meeting the increasing demand for electric vehicle and energy storage batteries in European markets, driven by ambitious decarbonization goals. For U.S. industries, this development could lead to increased competition in the global battery market, potentially influencing pricing and technological advancements. The establishment of these European plants also highlights the strategic importance of localized production to comply with evolving regulatory frameworks, such as those related to carbon footprint and recycled content. While these investments are currently impacting the profitability of Chinese firms, they are positioning them for long-term market dominance and resilience against trade barriers. The shift from 'selling batteries to Europe' to 'making batteries in Europe' could also influence U.S. companies' strategies for international expansion and supply chain diversification, as they too face pressures for localized production and sustainable practices.
What's Next?
Chinese battery manufacturers are expected to continue their aggressive expansion into Europe, with a focus on establishing integrated supply chains that include material sourcing and recycling facilities. CATL's Debrecen, Hungary, plant is slated for trial production of battery cells in September 2026, with full production commencing after extensive verification. Gotion is set to break ground on a 20 GWh LFP storage battery plant in Slovakia in October 2025, and its cathode material base in Kenitra, Morocco, indicates a move to secure upstream resources closer to European markets. The EU's tightening regulations, including mandatory battery passports from 2027 and increasing recycled material mandates from 2031, will further drive these localization efforts. Companies will need to navigate complex labor laws, environmental requirements, and policy uncertainties in Europe, which could prolong commissioning cycles and increase operational costs. The ongoing EU anti-subsidy investigation into Chinese batteries and the Net Zero Industry Act's local manufacturing requirements will also shape future investment decisions and operational strategies.
Beyond the Headlines
The strategic shift by Chinese battery manufacturers to establish comprehensive production ecosystems in Europe extends beyond mere manufacturing. It represents a proactive response to geopolitical and environmental pressures, aiming to create a closed-loop supply chain that encompasses material sourcing, cell production, and localized recycling. This vertical integration, exemplified by CATL's 'resource-material-cell' strategy in Indonesia and Gotion's cathode base in Morocco, is crucial for meeting stringent EU regulations on local content and supply chain transparency. The formation of industrial clusters around these European plants, attracting Chinese cathode material companies, equipment suppliers, and logistics providers, mirrors the development of battery industrial clusters in China. This trend could lead to a significant re-shaping of global manufacturing hubs, fostering new economic dependencies and technological collaborations. The long-term success of these ventures will depend on their ability to overcome cultural management complexities, adapt to diverse regulatory environments, and effectively integrate into local economies, ultimately transforming them from 'Chinese battery companies' into 'global battery companies'.