

What's Happening?
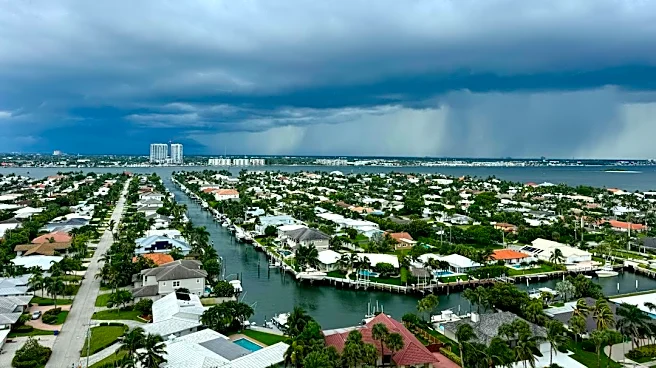
Florida homeowners navigate a unique and often complex insurance environment characterized by specific terminology and regulations, largely influenced by the state's susceptibility to hurricanes. Key terms include 'Citizens Property Insurance Corporation,'
a state-created non-profit insurer of last resort, which offers policies that can be transferred to private companies through 'takeout offers.' The process of 'underwriting' involves insurance companies assessing property risks based on factors like age, roof condition, and claims history. Policies also feature specialized components such as 'hurricane deductibles,' which are separate from standard 'all other perils (AOP) deductibles' and are typically a percentage of the dwelling coverage. Additionally, 'wind mitigation credits' are offered for homes with documented wind-resistant features, influencing premium costs. The state's building codes, particularly the Florida Building Code enacted in March 2002, play a significant role in insurance assessments and repair requirements, often necessitating 'ordinance or law coverage' to cover the extra costs of bringing damaged homes up to current code standards. Homeowners must also contend with 'binding moratoriums,' temporary pauses on new policies during storm threats, and understand the nuances of 'roof payment schedules' or 'actual cash value' clauses that can affect claim payouts for roof damage.
Why It's Important?
The intricate insurance landscape in Florida significantly impacts homeowners' financial stability and their ability to protect their most valuable asset. The prevalence of specialized terms and unique policy structures means that homeowners must be exceptionally diligent in understanding their coverage, deductibles, and exclusions. Misunderstanding these terms can lead to unexpected out-of-pocket expenses following a disaster, particularly given the high risk of hurricane damage. The role of Citizens Property Insurance Corporation as an insurer of last resort highlights market challenges, where private insurers may be reluctant to offer coverage in high-risk areas, potentially leaving homeowners with fewer options and higher costs. The availability of wind mitigation credits incentivizes homeowners to invest in property improvements that enhance resilience against storms, which can reduce both premiums and potential damage. However, the complexity of these policies, including varying roof payment schedules and the distinction between replacement cost and actual cash value, can create confusion and financial strain during the claims process, underscoring the critical need for clear communication and comprehensive policy review.
What's Next?
Florida homeowners will continue to face an evolving insurance market, driven by climate patterns and regulatory adjustments. It is crucial for policyholders to regularly review their declarations pages and understand any changes to their coverage, especially concerning hurricane deductibles, wind mitigation credits, and roof-related clauses. As the Atlantic hurricane season runs from June 1 to November 30, homeowners should proactively assess their coverage and gather necessary documents before the season begins to avoid issues like binding moratoriums. The state's ongoing efforts to manage Citizens Property Insurance Corporation, including depopulation and takeout offers, suggest a continued push to transition policies to the private market, which could alter coverage options and premiums for many. Homeowners should also stay informed about updates to the Florida Building Code, as these changes can impact repair costs and the necessity of ordinance or law coverage. Engaging with licensed insurance agents to compare policies and understand specific terms will remain essential for navigating this dynamic environment effectively.
Beyond the Headlines
The complexities of Florida's insurance market reflect broader challenges in managing climate-related risks within the U.S. property insurance sector. The state's unique situation, with its high exposure to hurricanes, serves as a microcosm for how other regions might adapt to increasing climate volatility. The reliance on a state-backed insurer like Citizens Property Insurance Corporation points to potential market failures where private industry struggles to price and underwrite risk effectively. This can lead to a delicate balance between ensuring affordable coverage for residents and maintaining the financial solvency of insurance providers. Furthermore, the emphasis on wind mitigation and building codes highlights a growing trend towards proactive risk reduction through structural improvements, which could become a national model for resilience. The ongoing dialogue between homeowners, insurers, and regulators in Florida will likely influence future policy decisions and insurance product development across other vulnerable U.S. regions, shaping how communities adapt to and finance protection against natural disasters.