

What's Happening?
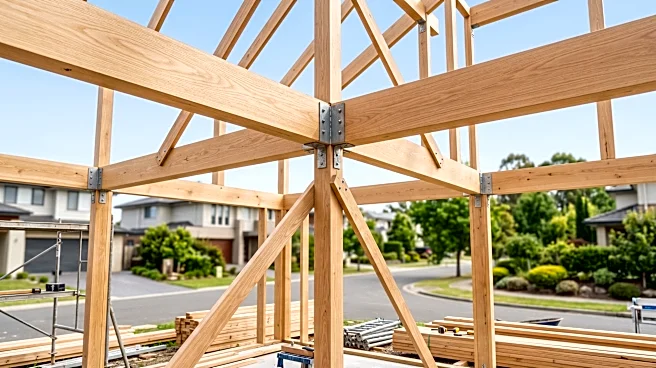
Fannie Mae has specific requirements for conventional single-close construction-to-permanent financing, which combines construction financing and a permanent mortgage into one transaction. For these loans, Fannie Mae mandates that lenders underwrite based
on the permanent financing terms. While the primary advantage is a single closing, borrowers should be aware that their financial circumstances can still trigger requalification during construction. Requalification may be necessary if the property value declines or if certain loan terms or credit documents change. The process involves a comprehensive evaluation of the borrower's financial profile, including income, debts, credit, and assets, as well as the proposed construction project's details, such as the land, builder, plans, budget, and an 'as-completed' appraisal. The appraisal assesses the property's value upon completion, which directly influences the loan-to-value calculation.
Why It's Important?
These guidelines are crucial for both lenders and borrowers involved in new home construction, ensuring that the financing process is robust and risk-managed. For borrowers, understanding these requirements upfront is essential to avoid complications and potential requalification issues during the construction phase. The emphasis on underwriting based on permanent financing terms provides a more stable financial outlook for the project. The detailed evaluation of the construction project itself, including the builder's qualifications and a comprehensive budget, helps protect all parties by ensuring the project is viable and well-planned. This structured approach aims to mitigate risks associated with construction delays, cost overruns, or changes in borrower financial stability, which are common challenges in construction lending. It also ensures that the final property value supports the loan amount, safeguarding the investment.
What's Next?
Borrowers considering a One-Time Close construction loan should engage with a lender early in the process, ideally before purchasing land or finalizing builder contracts. This allows for a clear understanding of the specific requirements for their project and financial situation. It is critical for borrowers to maintain financial stability throughout the construction period, avoiding new debt or significant changes in employment that could trigger requalification. Lenders will continue to require detailed documentation for both the borrower and the construction project, including plans, specifications, and a budget. The 'as-completed' appraisal will remain a key factor in determining the final loan amount. Adherence to these guidelines will be vital for a smooth transition from construction financing to permanent mortgage.
Beyond the Headlines
Fannie Mae's detailed framework for One-Time Close construction loans reflects a broader effort to standardize and de-risk the complex process of financing new home builds. By integrating construction and permanent financing, these loans aim to simplify the experience for borrowers, but the underlying requirements highlight the inherent uncertainties in construction. The potential for requalification during construction underscores the dynamic nature of financial markets and property values, even after initial approval. This approach also implicitly encourages borrowers to work with reputable builders and to have well-defined project plans, promoting quality construction and realistic budgeting. The guidelines serve as a testament to the need for comprehensive due diligence in real estate development, ensuring that both the financial and physical aspects of a new home are sound.