


What's Happening?
Mortgage rates have shown meaningful improvement over the past month, with Mortgage News Daily’s 30-year benchmark falling from 7.61% in early October to 7.17% by Thursday. This decline occurred despite a stronger-than-expected October jobs report, which
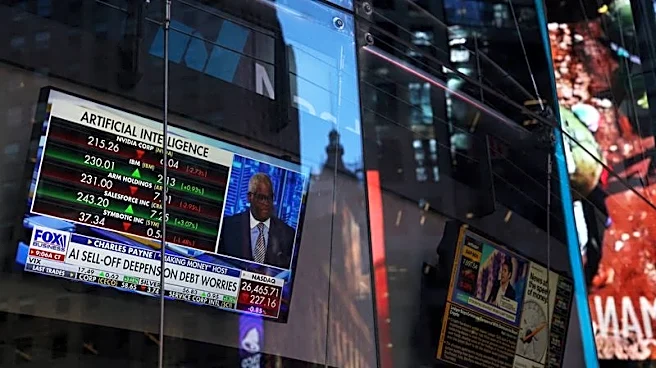
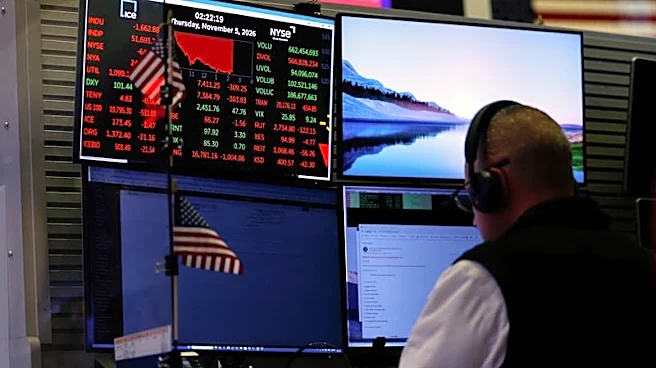
typically would push bond yields higher. The improvement is largely attributed to a sharp sell-off in technology and AI-related stocks, particularly a 5.5% drop in the Nasdaq. This led investors to seek the relative safety of U.S. Treasury bonds, causing yields to fall and benefiting mortgage-backed securities. The 10-year Treasury yield, a key driver of mortgage rates, decreased to 4.84% from approximately 5.3% in early October. While the jobs report showed 165,000 jobs added in October and unemployment falling to 4.1%, the bond market's reaction was tempered by the equity market's decline.
Why It's Important?
The current market dynamics highlight the complex interplay of various economic factors influencing mortgage rates. While strong economic indicators like job growth usually suggest higher interest rates, the flight to safety in the bond market due to stock volatility has counteracted this effect. This situation offers a temporary reprieve for potential homebuyers and those considering refinancing, as financing conditions have improved from their October highs. However, the underlying economic strength and inflation expectations remain critical. The ability of the bond market to absorb a strong jobs report without a significant rate hike indicates a nuanced investor sentiment, where broader economic uncertainty and equity market performance can override traditional responses to labor data. This could lead to increased purchasing power for some, as a 0.50% improvement in rate can increase purchasing power by roughly 5%.
What's Next?
The stability of current mortgage rates is not guaranteed, as future inflation reports, specifically the Consumer Price Index (CPI) and Producer Price Index (PPI), along with Treasury auctions and housing-market data, could quickly alter the landscape. These upcoming economic data releases will be crucial in shaping expectations for Federal Reserve policy and influencing mortgage pricing. Homebuyers with near-term closing dates are advised to consult with their loan officers regarding lock strategies, rather than assuming the recent gains will continue. Homeowners with high-interest credit cards might consider debt consolidation through home equity options, though they should carefully weigh the risks. The market will continue to be influenced by competing forces: labor-market strength, inflation expectations, Federal Reserve policy, and investor demand for safer assets.
Beyond the Headlines
The current scenario underscores a shift in how various economic signals are interpreted by financial markets. The traditional correlation between strong job growth and rising interest rates has been disrupted by significant movements in the equity market, particularly in the technology sector. This suggests that investor confidence and risk appetite in different asset classes can have a profound and immediate impact on borrowing costs, even overriding otherwise positive economic news. This dynamic could lead to increased market volatility and unpredictability in mortgage rate movements, making it more challenging for consumers and lenders to forecast future trends. It also highlights the growing influence of specific sector performance, like technology and AI, on broader financial stability and interest rate environments.