
What's Happening?
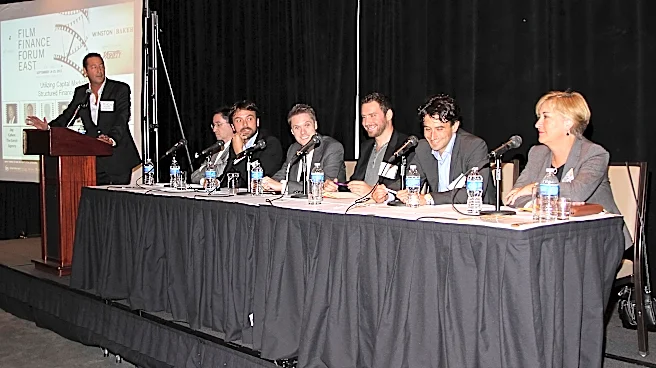
Supercoin, a stablecoin infrastructure developer, is pursuing regulatory approval to introduce a Kenyan shilling-backed stablecoin. This initiative was announced by Supercoin Managing Director Gideon Greaves at the Africa Stablecoin Summit 2026 in Cape
Town, South Africa. The company has submitted a licensing application in Kenya to facilitate the introduction of this digital currency, which would allow businesses to conduct transactions using a digital representation of the shilling. The summit, attended by 546 delegates from central banks, commercial banks, regulators, fintech companies, and payment service providers, focused on the potential of blockchain-based currencies to enhance cross-border payments and reduce inefficiencies in regional financial transactions across Africa. Currently, dollar-denominated tokens dominate approximately 99% of the global stablecoin market, which has grown from about USD 5 billion in 2020 to USD 290 billion. Supercoin has already launched ZARsc, a South African rand-backed stablecoin, and Supercoin Mint, a platform for issuing and redeeming digital currency against rand deposits.
Why It's Important?
The introduction of local currency-backed stablecoins, such as the proposed Kenyan shilling stablecoin, could significantly impact financial transactions in African markets. The current dominance of dollar-backed stablecoins raises questions about the role of local currencies in digital finance and their implications for monetary policy and financial regulation. By providing digital payment infrastructure for African currencies, Supercoin aims to improve their accessibility in regional and international transactions, potentially reducing costs, delays, and foreign exchange challenges associated with cross-border payments. This move could foster greater financial inclusion and efficiency within African economies, allowing businesses and consumers to transact more seamlessly. The initiative also highlights a broader trend of exploring digital alternatives to traditional financial systems, which could reshape how money moves across borders and within local economies.
What's Next?
The next step for Supercoin's Kenyan shilling-backed stablecoin is securing regulatory approval in Kenya. The successful introduction of this stablecoin will also depend on the development of supporting financial infrastructure and its integration with existing payment systems, particularly mobile money networks that are prevalent in many African markets. Discussions at the summit emphasized the importance of connecting stablecoins to these established payment channels to ensure wider adoption and impact. Stakeholders, including central banks and regulators, will need to address concerns related to anti-money laundering requirements, financial crime prevention, reserve assurance, custody arrangements, liquidity management, and consumer protection. The outcome of these regulatory processes and infrastructure developments will determine the timeline and scope of the stablecoin's rollout and its potential to transform digital payments in Kenya and beyond.
Beyond the Headlines
The push for local currency-backed stablecoins in Africa represents a significant shift towards digital sovereignty in financial technology. While dollar-backed stablecoins have dominated the global market, initiatives like Supercoin's aim to empower local currencies with the same speed and reach on-chain. This could lead to a re-evaluation of monetary policy frameworks in African nations as central banks consider how to manage digital representations of their currencies. Furthermore, the integration of stablecoins with mobile money networks could bridge the gap between traditional and digital finance, potentially accelerating financial inclusion for unbanked and underbanked populations. The ethical implications revolve around ensuring robust consumer protection and preventing financial crime in a rapidly evolving digital landscape, while the legal framework for these new digital assets will need to adapt to support innovation while mitigating risks.