

What's Happening?
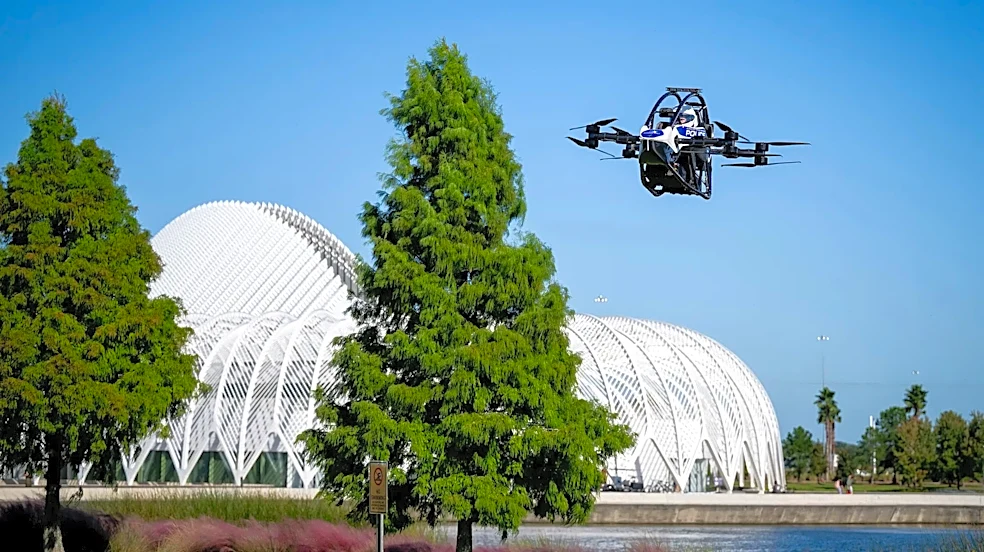
Joby Aviation, Inc. (JOBY), a developer of electric vertical takeoff and landing (eVTOL) aircraft, experienced a significant drop in its stock price, falling 8.52% to $5.26. This decline occurred after Barclays downgraded the company's rating to 'Underweight'
and reduced its price target from $6 to $4. Barclays cited several concerns, including Joby's payload capacity, its ability to scale manufacturing, its cash burn rate, and what it considers an 'unjustified' premium valuation. The analyst firm also questioned Joby's strategy of simultaneously manufacturing, operating, and servicing its own aircraft in a nascent market. This stock-specific downturn for Joby Aviation contrasted with the performance of its rivals, Archer Aviation (ACHR) and EHang (EH), both of which saw their stock prices rise by approximately 5% on the same day, following more favorable analyst coverage from Barclays for Archer.
Why It's Important?
This downgrade and subsequent stock decline are significant for the emerging eVTOL industry and Joby Aviation's position within it. Barclays' analysis highlights critical challenges that eVTOL companies face beyond just achieving certification, such as manufacturing scalability, operational complexity, and financial sustainability. The firm's skepticism about Joby's payload capacity suggests potential limitations in the types of services or markets the company can effectively address. Furthermore, the concern over cash burn and valuation indicates that investors and analysts are scrutinizing the financial models and long-term viability of these innovative but capital-intensive ventures. The divergence in stock performance between Joby and its competitors, particularly Archer Aviation, underscores a growing debate within the sector regarding whether early certification alone guarantees market leadership, or if other factors like manufacturing capability and financial discipline will ultimately determine success. This shift in analyst sentiment could influence investor confidence and capital allocation across the eVTOL market.
What's Next?
Investors and industry observers will closely monitor several key areas for Joby Aviation. The company's progress toward FAA certification remains a critical factor, as does its ability to manage cash spending effectively. Upcoming earnings reports will be scrutinized for signs of scaling revenue from its early commercial activities, such as its Blade passenger service, and for updates on its manufacturing readiness. Any further analyst shifts or regulatory developments within the eVTOL sector could also trigger significant stock movements. Joby's ongoing lawsuit against rival Archer Aviation also represents an unresolved factor that could impact its financial and operational outlook. The company's strategy to acquire Resonant Sciences for approximately $500 million, primarily in cash, will also be watched to see how it impacts Joby's overall financial health and its ability to offset current losses.
Beyond the Headlines
The Barclays downgrade of Joby Aviation touches upon deeper implications for the advanced air mobility sector. The analyst's questioning of Joby's 'winner takes all' market assumption suggests a more fragmented and competitive future for eVTOLs than initially envisioned by some. The challenge of balancing manufacturing, operations, and servicing in a new market highlights the immense logistical and operational hurdles that these companies must overcome. This situation also brings to light the ethical considerations of valuation in a pre-revenue, high-growth industry, where speculative investments are common. The emphasis on factors like payload capacity and manufacturing scale, rather than just technological innovation, indicates a maturing industry where practical execution and financial prudence are becoming paramount. This could lead to a consolidation phase in the future, where only companies with robust operational strategies and sufficient capital can survive and thrive.