

What's Happening?
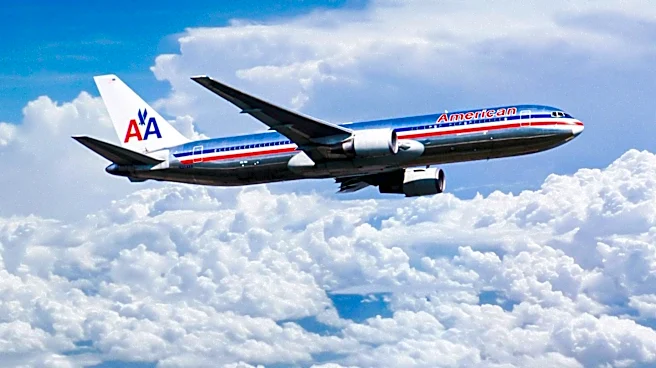
Investment analysts at Freedom Broker have reduced their price target for American Airlines Group (NASDAQ:AAL) stock from $18.00 to $17.00. Despite this reduction, the firm maintains a 'buy' rating on the airline's stock, suggesting a potential upside
of 35.14% from its previous closing price. This adjustment comes amidst other analyst revisions, with JPMorgan Chase & Co. increasing their price target to $24.00, while The Goldman Sachs Group cut theirs to $11.00 with a 'sell' rating. Rothschild & Co Redburn lifted their price objective to $13.50 with a 'neutral' rating, and Melius Research downgraded the stock from 'buy' to 'hold' while boosting their price objective to $19.00. Susquehanna also lowered its price objective to $15.00 but maintained a 'positive' rating. The consensus rating for American Airlines Group among analysts is currently 'Hold', with an average price target of $17.28.
Why It's Important?
The varied adjustments in price targets from different investment firms highlight the uncertainty and diverse perspectives surrounding American Airlines Group's financial outlook. A lower price target from Freedom Broker, even with a 'buy' rating, could influence investor sentiment and potentially lead to short-term stock volatility. The airline's recent financial performance shows a negative net margin of 0.79% and a negative return on equity of 9.11%, indicating ongoing challenges. However, American Airlines Group did report better-than-expected quarterly earnings, with an EPS of ($0.28) against a consensus estimate of ($0.36), and revenue of $16.34 billion, surpassing analysts' expectations. These mixed signals suggest that while the company is navigating a difficult economic environment, there are also signs of operational resilience. The consensus 'Hold' rating reflects a cautious approach from the broader analyst community, indicating that while the stock may not be a strong 'buy' for everyone, it's also not seen as a definitive 'sell' by most.
What's Next?
Investors will closely monitor American Airlines Group's future earnings reports and operational updates for further indications of its financial health and recovery trajectory. The company's ability to manage its negative net margin and improve its return on equity will be critical for long-term investor confidence. Analyst ratings and price targets will likely continue to fluctuate based on market conditions, fuel prices, travel demand, and the airline's strategic initiatives. Insider trading activities, such as the recent sale of shares by SVP Angela Owens, will also be watched for insights into executive sentiment. Furthermore, the broader economic environment and any changes in travel restrictions or consumer behavior will significantly impact the airline's performance and, consequently, its stock valuation. The company is projected to post -1.30 earnings per share for the current fiscal year, suggesting continued challenges ahead.
Beyond the Headlines
The airline industry, including American Airlines Group, faces systemic challenges beyond immediate financial metrics, such as fluctuating fuel costs, labor negotiations, and the ongoing need for significant capital investment in fleet modernization and technology. The competitive landscape, with other major carriers vying for market share, also puts pressure on pricing and profitability. The long-term viability of airlines like American Airlines Group depends not only on their ability to cut costs and increase revenue but also on their adaptability to evolving passenger expectations, including sustainability initiatives and enhanced customer experience. The varying analyst opinions underscore the inherent risks and opportunities in the airline sector, where external factors can rapidly alter a company's fortunes. The company's market capitalization of $8.34 billion and a P/E ratio of -17.23 further highlight the speculative nature of investing in the airline industry during periods of economic uncertainty.