

What's Happening?
Manhattan's office vacancy rate decreased to 12.6% in the third quarter, marking its lowest point since before 2020, according to Commercial Observer. This figure represents a decline from 13.1% in the second quarter and 14.7% a year prior. Concurrently,
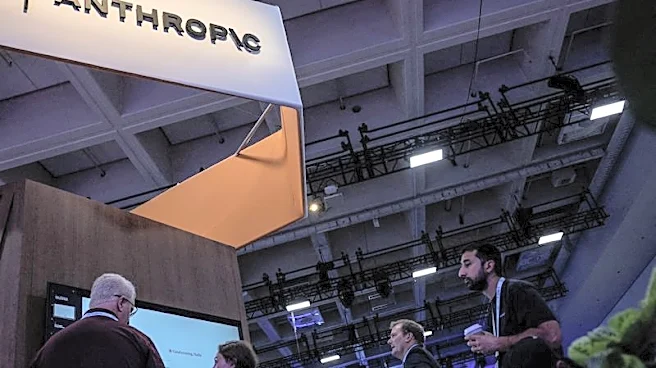
office leasing volume in Manhattan saw a 2.3% increase year-over-year in Q3, and the direct asking rent climbed to $84.56 per square foot. The demand for office space is broad-based, spanning various industries including finance, law, and technology. Notable deals contributing to this trend include American Express's new headquarters at 2 World Trade Center and Anthropic's lease at 330 Hudson Street. Brokers indicate that the primary constraint in the market is the limited supply of new construction, with only about 7.9 million square feet projected for delivery between 2028 and 2032.
Why It's Important?
The significant drop in Manhattan's office vacancy rate signals a robust recovery and renewed confidence in the city's commercial real estate market, particularly after the disruptions of recent years. This trend is crucial for the U.S. economy as Manhattan is a major financial and business hub. Increased leasing activity and rising asking rents suggest a healthy demand for physical office spaces, which can lead to job growth, increased economic output, and higher property tax revenues for the city. The broad-based demand across diverse sectors indicates that the recovery is not reliant on a single industry, making it more resilient. However, the warning from brokers about Class B rents stretching tenants and the limited new supply could lead to affordability challenges for some businesses, potentially impacting smaller firms or those with tighter budgets. This dynamic could also drive further investment into upgrading existing office stock to meet modern demands.
What's Next?
With the current low vacancy rates and limited new construction pipeline, Manhattan's office market is likely to experience continued upward pressure on rents. Landlords are reporting steady momentum, with some firms logging consistent quarters of leasing above their five-year averages. The return-to-office trend, with many workers back in the office three to five days a week, is a significant driver of this demand, as employers seek to accommodate their workforce. This sustained demand, coupled with constrained supply, could lead to further rent increases, particularly for premium Class A spaces. Developers might explore opportunities for adaptive reuse of older buildings or strategic new constructions to meet future demand, though the long lead times for such projects mean immediate supply relief is unlikely. The market will also be watching how the balance between tenant affordability and landlord profitability evolves in this tightening market.
Beyond the Headlines
The resurgence of Manhattan's office market challenges earlier predictions of a permanent shift away from traditional office work, highlighting the enduring value of physical workspaces for collaboration, culture, and innovation, especially in high-value industries like finance and tech. The emphasis on Class A spaces and the willingness of major corporations to commit to significant leases, including outright purchases like American Express, suggest a flight to quality and a long-term commitment to physical presence. This trend could exacerbate the divide between prime and secondary office markets, potentially leaving older, less desirable office buildings struggling with higher vacancies. The return-to-office movement also has broader implications for urban economies, impacting everything from public transportation ridership to local retail and dining establishments. The sustained demand for office space in Manhattan underscores its unique position as a global business center, where the benefits of in-person interaction continue to outweigh the perceived advantages of fully remote work for many organizations.