



What's Happening?
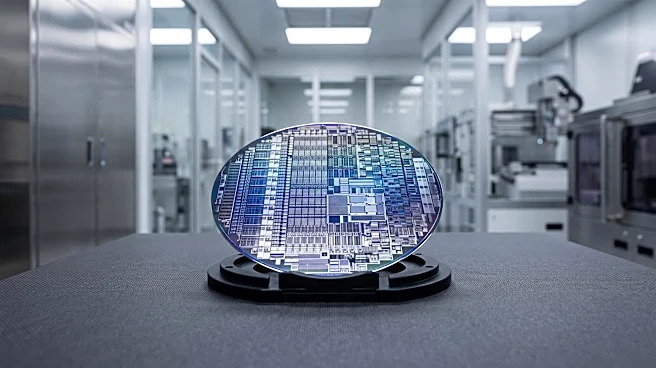
According to Bank of America's November Global Fund Manager Survey, betting on semiconductor stocks continues to be the market's most crowded trade. However, the proportion of respondents identifying it as such has significantly decreased, falling from
82% in July to 39% in November. Despite this reduction in conviction, semiconductor stocks still hold the top spot, with the next closest crowded trades being betting against Chinese equities (14%) and betting on the 'Magnificent Seven' (12%). The survey, conducted from November 6 to 12, included 193 panelists managing $526 billion. It also indicated that managers made their largest cut to technology overweights since 2006. A significant 52% of respondents anticipate a major cloud provider announcing a capital spending cut within the next six months, an increase from 30% in October. The most frequently cited market tail risks were an AI bubble (34%) and a credit event at a major cloud provider (31%).
Why It's Important?
This survey highlights a shifting sentiment among global fund managers regarding the semiconductor sector, a critical component of the U.S. technology industry. While semiconductors remain a favored investment, the declining percentage of managers who view it as the most crowded trade suggests a potential cooling of enthusiasm or a diversification of investment strategies. The significant cut in technology overweights since 2006 indicates a broader re-evaluation of the tech sector, which could impact valuations and investment flows into U.S. tech companies. The expectation of capital spending cuts from major cloud providers is particularly significant, as these companies are major consumers of advanced chips. Such cuts could signal a slowdown in demand for semiconductors, potentially affecting the revenue and profitability of chip manufacturers and their suppliers. This cautious outlook could lead to increased volatility in semiconductor stocks and broader technology markets.
What's Next?
The immediate focus for investors will be on announcements from major cloud providers regarding their capital spending plans. Any confirmed cuts could directly impact future chip orders and further dampen sentiment around semiconductor stocks. The survey's findings suggest that while semiconductors are still seen as a strong play, the market is becoming more discerning, and the 'crowded trade' status might be more a reflection of past momentum than current conviction. Investors will also be monitoring the broader technology sector for signs of continued de-risking or reallocation of capital. The concerns about an AI bubble and potential credit events at cloud providers indicate that market participants are wary of potential downside risks, which could lead to more conservative investment decisions in the near term. The evolution of these trends will shape the performance of U.S. technology and semiconductor stocks in the coming months.
Beyond the Headlines
The survey results point to a potential inflection point in the investment landscape for the U.S. technology sector, particularly semiconductors. The reduced conviction in the 'most crowded trade' status, coupled with significant cuts in technology overweights, could signal a broader market rotation away from high-growth tech stocks towards other sectors, or a more selective approach within tech. This shift might be driven by a re-evaluation of long-term growth prospects for AI infrastructure spending, especially if economic conditions tighten. The increasing concern about an 'AI bubble' suggests that investors are becoming more critical of valuations and the sustainability of current growth rates. This could lead to a more mature phase for AI investments, where companies with clear profitability and sustainable business models are favored over those with speculative growth narratives. The implications extend to the broader U.S. economy, as the tech sector's performance often influences overall market sentiment and innovation cycles.