
What's Happening?
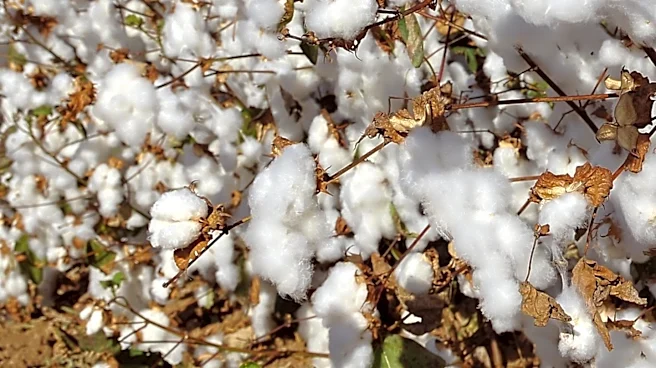
Global cotton stocks are projected to fall to their lowest level since the 2011/12 crop year, according to the latest USDA report. This anticipated decline is primarily due to a smaller global harvest and consistent mill-use numbers, indicating a production
deficit of 5.6 million bales, the largest shortfall since 2020/21. The December NY/ICE futures contract for cotton saw prices increase from 84 to 88 cents/lb over the past month, reaching a high of 93 cents/lb in late August before a slight retreat. Prices for other 2026/27 NY/ICE contracts, such as March, May, and July, are currently higher than December, with May values near 91 cents/lb. The A Index briefly surpassed 100 cents/lb before settling around 96 cents/lb. The USDA report included a small decrease in the global production forecast for 2026/27 by 317,000 bales to 117.3 million, while global mill-use remained largely unchanged at 122.9 million bales. Revisions to previous crop years increased 2026/27 beginning stocks by 502,000 bales to 75.3 million, resulting in a net projected ending stock of 69.9 million bales.
Why It's Important?
The projected decline in global cotton stocks to a 15-year low has significant implications for the textile industry, consumers, and agricultural markets worldwide, including the U.S. Tighter supply typically leads to higher prices, which can increase manufacturing costs for apparel and other cotton-based products. This cost increase may eventually be passed on to consumers, impacting household budgets. For U.S. cotton farmers, higher prices could offer improved profitability, but the U.S. production forecast itself saw a decrease of 407,000 bales to 13.2 million, indicating domestic supply challenges. The global trade forecast increased, with significant changes in import and export figures for various countries, suggesting shifts in international cotton flows. The current environment, with consumption potentially exceeding 120 million bales for back-to-back years, highlights a robust demand that is now confronting a constrained supply. This dynamic creates uncertainty for businesses reliant on cotton, from growers to retailers, as they navigate fluctuating prices and supply chain disruptions.
What's Next?
The price outlook for cotton will largely depend on how the supply-demand balance evolves throughout the 2026/27 crop year. While tighter stocks generally support higher prices, the extent to which demand will follow these price increases remains to be seen. The market will closely watch high-frequency indicators such as China's ongoing reserve sales, which have shown strong demand despite rising auction prices. If China needs to replenish its reserves from the global market, it could further tighten exporter stocks and push prices higher. Conversely, weak U.S. export sales data in recent weeks, despite the upward price movement, suggests that mills are cautious about committing to new obligations at current price levels. The absence of a sharp swing in macroeconomic conditions or massive stimulus, unlike previous periods of high cotton prices, indicates that the current demand environment might be less urgent. Stakeholders will need to monitor global production forecasts, mill-use estimates, and international trade patterns to anticipate future price movements and adjust their strategies accordingly.
Beyond the Headlines
The anticipated scarcity of global cotton stocks carries deeper implications for sustainability and economic resilience. The reliance on a single commodity like cotton for a vast global industry highlights vulnerabilities to climate change, geopolitical events, and agricultural policies that can impact crop yields. This situation could accelerate the shift towards alternative fibers or more sustainable cotton production methods, as industries seek to mitigate supply risks and reduce their environmental footprint. Furthermore, the price volatility could disproportionately affect developing countries that are major cotton producers or textile manufacturers, impacting their economies and livelihoods. The current scenario also underscores the complex interplay between agricultural markets, global trade, and consumer behavior. As prices rise, there might be a renewed focus on domestic production capabilities and supply chain diversification to reduce dependence on international markets. This could lead to long-term strategic adjustments in the textile industry, emphasizing resilience and localized sourcing in the face of global uncertainties.