

What's Happening?
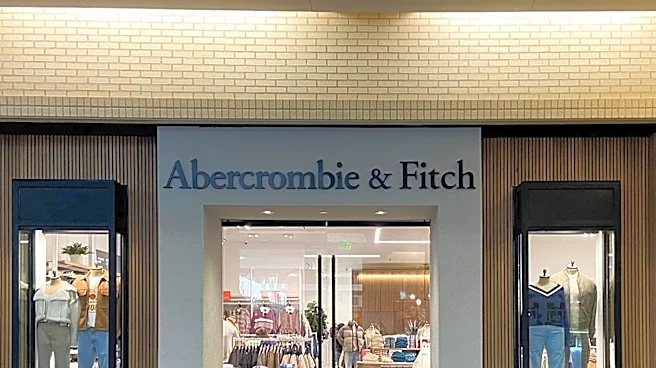
Abercrombie & Fitch Co. (ANF) stock is currently trading at $141.40, which is 19.4% above GuruFocus' intrinsic value estimate of $118.43, classifying it as modestly overvalued. This assessment comes despite the company's recent strong performance, including
a 4.0% stock rally and a positive earnings surprise. Abercrombie & Fitch reported earnings per share (EPS) of $2.42, significantly exceeding the Zacks Consensus Estimate of $1.95, marking a 24.1% positive earnings surprise. Revenue also surpassed expectations, reaching $1.27 billion, and the company has achieved its 15th consecutive quarter of sales growth. The Abercrombie brand sales increased by 8%, with comparable sales up 4%. However, insider activity shows a significant sell-off, with $50.3 million worth of shares sold over the past 12 months and no buying activity reported by insiders. The company's GF Score™ is 86/100, indicating strong fundamentals, particularly in growth and momentum, but with weaker areas in financial strength and valuation.
Why It's Important?
The overvaluation of Abercrombie & Fitch stock, as indicated by GuruFocus, suggests potential risks for investors, particularly given the limited margin of safety at its current price point. While the company's consistent sales growth and strong earnings beat demonstrate a successful turnaround and robust operational performance, the discrepancy between its market price and intrinsic value raises concerns about sustainability. The significant insider selling activity further complicates the investment outlook, as it could signal a lack of confidence from those most familiar with the company's internal workings. This situation highlights a critical challenge for investors: balancing strong current performance and growth prospects against valuation metrics and insider sentiment. The company's ability to maintain its growth trajectory and profitability will be crucial in justifying its elevated stock price and mitigating the perceived overvaluation, especially as it continues to expand its brands and omnichannel presence.
What's Next?
Investors will closely monitor Abercrombie & Fitch's future earnings reports and sales figures to see if the company can continue to outperform expectations and grow into its current valuation. The company's strategy of expanding its brands, such as the Hollister partnership with Target and the NFL partnership, will be key to sustaining growth beyond its core retail operations. Management's commitment to at least $500 million in share repurchases for the full year could provide some support for the stock price by reducing the number of outstanding shares. However, the ongoing insider selling trend will likely remain a point of scrutiny, potentially influencing investor sentiment. The market will also be watching for any shifts in the GF Value™ and GF Score™ to assess whether the stock's valuation aligns more closely with its fundamentals in the coming quarters. The company's ability to navigate changing consumer preferences and maintain its brand relevance will be crucial for its long-term performance.
Beyond the Headlines
The situation with Abercrombie & Fitch reflects a broader trend in the retail sector where companies are undergoing significant transformations to adapt to evolving consumer behaviors and market dynamics. Abercrombie's successful turnaround, moving from a 'dead mall' narrative to consistent sales growth, demonstrates the potential for established brands to reinvent themselves through strategic initiatives like omnichannel integration and brand diversification. However, the current overvaluation and insider selling highlight the inherent volatility and speculative nature of the stock market, even for companies with strong operational performance. This scenario underscores the importance of comprehensive due diligence for investors, looking beyond immediate earnings beats to consider long-term valuation, insider confidence, and broader market sentiment. The challenge for Abercrombie & Fitch will be to prove that its recent success is not merely a temporary resurgence but a sustainable model for growth in a highly competitive retail landscape, potentially setting a precedent for other legacy brands seeking revitalization.