


What's Happening?
Cashierless payment technologies are experiencing significant expansion, particularly in vending machines located in urban centers with dense vending networks and advanced payment ecosystems. This trend is driven by the demand for convenience, speed,
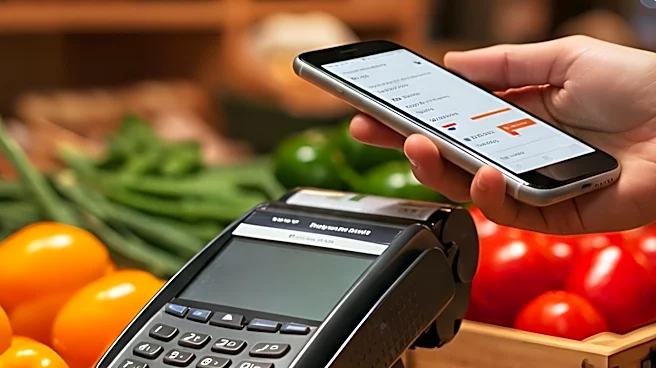
and enhanced security in transactions. AI-enabled vending solutions are being deployed to improve reliability and user experience, especially in emerging markets where staffed support might be limited. These systems leverage artificial intelligence for various functions, including fraud detection, ensuring secure cashless payment experiences, and offering personalized consumer engagement. Beyond vending, contactless payment technologies are broadening to encompass mobile wallets, QR-based payments, and Near-Field Communication (NFC) enabled devices. Merchants are increasingly prioritizing these contactless options to reduce checkout friction, minimize queue times, and potentially increase basket sizes, especially in high-traffic environments like quick-service restaurants and transit networks. The shift represents a broader transformation in the payments value chain, impacting aspects from onboarding to data analytics.
Why It's Important?
The widespread adoption of cashierless and contactless payment technologies signifies a major shift in consumer transaction behavior and merchant operations across the U.S. and globally. For consumers, it offers increased convenience and speed, reducing wait times and simplifying the purchasing process. The enhanced security features, such as tokenization and biometric verification, also build greater trust in digital transactions. For businesses, particularly in retail, hospitality, and transit, these technologies lead to improved operational efficiency through reduced cash handling, lower maintenance costs, and faster checkout times, which can boost labor productivity and throughput. Merchants with omnichannel strategies benefit from unified payment experiences, minimizing fragmentation across physical and digital sales channels. The integration of loyalty programs and personalized offers within these digital payment systems also allows for richer data collection, enabling more targeted marketing and increased customer engagement. This evolution is crucial for businesses aiming to stay competitive and meet evolving consumer expectations for seamless and secure payment experiences.
What's Next?
The future will likely see continued innovation and broader integration of cashierless and contactless payment solutions across various sectors. Expect further advancements in digital wallet ecosystems, cloud-based payment orchestration, and secure element technologies, which will expand the capabilities and adoption of these payment methods. Cloud-based tokenization will simplify the onboarding of new devices and payment methods, leading to faster merchant rollouts and more frequent feature updates. On the consumer side, devices equipped with NFC, QR-code scanning, and biometric sensors will continue to deliver smoother experiences, even in areas with unreliable network connections. New business models are expected to emerge around contactless acceptance, including cloud-based point-of-sale (POS) platforms and subscription-based device management, which will reduce upfront capital expenditures for merchants. Furthermore, increased data connectivity between payment platforms and loyalty programs will become standard, fostering stronger cross-sell opportunities and personalized promotions while maintaining privacy considerations. Regulatory bodies will likely continue to focus on data privacy and consumer rights in payment data handling, prompting providers to implement transparent privacy controls.
Beyond the Headlines
The shift towards cashierless payments extends beyond mere transaction convenience, touching upon deeper societal and economic implications. Ethically, the increased reliance on digital payments raises questions about financial inclusion for individuals without access to banking services or smartphones, potentially creating a digital divide. Privacy concerns are also paramount, as these systems collect vast amounts of consumer data, necessitating robust regulations and transparent data handling practices to prevent misuse. Legally, the evolving landscape of digital payments requires continuous adaptation of existing laws concerning fraud, consumer protection, and data security. Culturally, the move away from physical cash could alter consumer habits and perceptions of value, potentially leading to a more frictionless, yet less tangible, relationship with money. In the long term, this trend could accelerate the development of a truly cashless society, impacting everything from small business operations to national economic policies and the very nature of financial transactions.