
What's Happening?
A growing number of Gen Z individuals are adopting a financial strategy termed 'retirement-maxxing,' which involves prioritizing early and aggressive retirement savings and investing. This trend reflects a desire for financial independence and security,
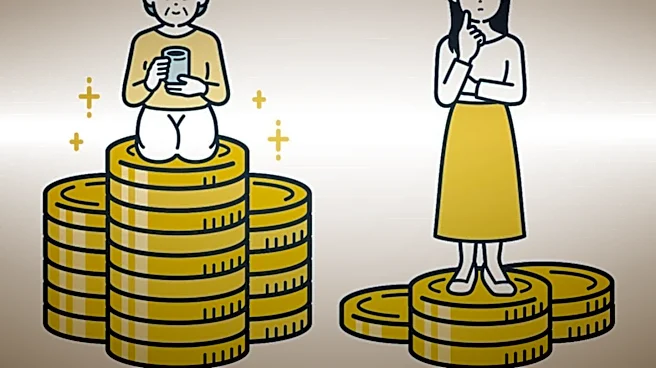
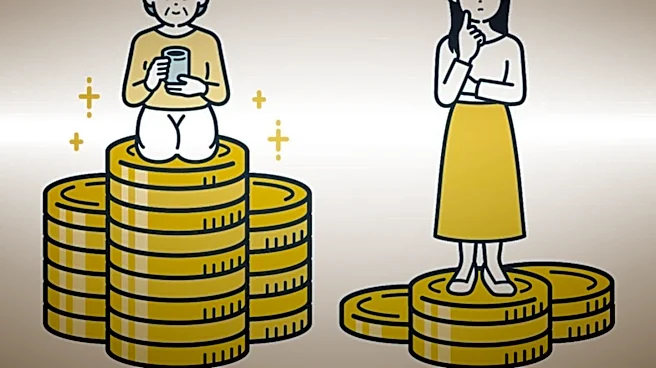
influenced by growing up in an environment of high housing costs, unpredictable expenses, and witnessing financial crises. While the concept of saving early is not new, Gen Z is distinguishing itself by choosing to save substantial portions of their income rather than immediately increasing their lifestyle spending. Many are contributing as much as possible to workplace retirement plans and IRAs, or automating portions of their paychecks into savings and investments. This approach leverages the power of compound growth, allowing investments to grow significantly over a long period, which is a key advantage for those starting in their 20s.
Why It's Important?
The 'retirement-maxxing' trend among Gen Z has significant implications for individual financial well-being and the broader economy. By starting early, young investors can accumulate substantial wealth over their lifetimes, potentially achieving financial independence sooner than previous generations. This proactive approach to saving could lead to a more financially secure future for this demographic, reducing reliance on social safety nets in retirement. For financial institutions, this trend presents opportunities to develop tailored investment products and educational resources for young investors. However, it also highlights a potential shift in consumer spending patterns, as a focus on aggressive saving might temper immediate consumption, impacting various industries that rely on discretionary spending. The emphasis on financial literacy and early investing could also foster a more financially savvy generation, influencing future economic behaviors and market dynamics.
What's Next?
Financial advisors emphasize that while aggressive saving is beneficial, Gen Z should also balance retirement-maxxing with other life goals and financial fundamentals. Key recommendations include building an emergency fund to cover several months of essential expenses, managing high-interest debt like credit card balances, and establishing good credit. Taking full advantage of employer retirement plan matches is also crucial, as it provides an immediate boost to savings. Advisors suggest exploring Roth versus traditional retirement accounts based on individual circumstances and considering investments outside of retirement accounts for more flexible, near-term goals like home purchases or starting a business. The challenge for Gen Z will be to navigate the vast amount of financial information available online, distinguishing reliable advice from potentially unrealistic or risky trends promoted on social media, and seeking guidance from qualified financial professionals.
Beyond the Headlines
The emergence of 'retirement-maxxing' reflects a deeper generational response to economic uncertainties and a heightened awareness of financial planning. Unlike previous generations, Gen Z has grown up with unprecedented access to financial information through budgeting apps, investing platforms, and social media. This access, while empowering, also necessitates critical discernment to avoid misinformation. The trend suggests a potential redefinition of success, moving beyond immediate gratification towards long-term financial security and independence. This could lead to cultural shifts in how wealth is perceived and pursued, with a greater emphasis on prudent financial habits from a young age. The long-term impact could be a generation that is more resilient to economic downturns and better prepared for retirement, potentially altering societal expectations around work, leisure, and financial responsibility.