

What's Happening?
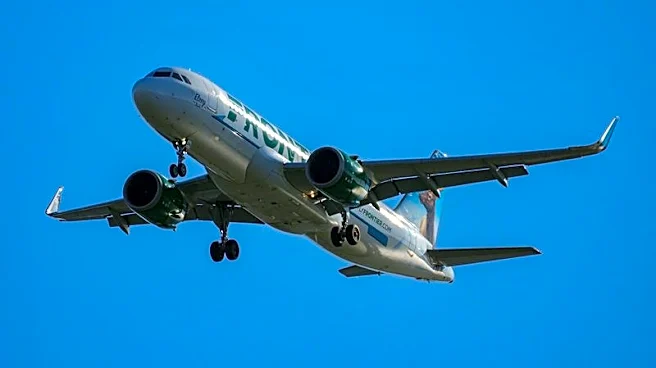
SkyWest (NASDAQ:SKYW) announced its third-quarter 2026 financial results, reporting a net income of $120 million, or $3.08 per diluted share. This performance was driven by increased block-hour demand from its airline partners, leading to a 6% rise in total
revenue year-over-year, reaching $1.1 billion. However, the company's prorate business was significantly impacted by elevated fuel costs. Prorate fuel expense surged to $66 million in Q3 2026, up from $34 million in the same period last year, primarily due to higher fuel prices and increased prorate production. As a result of these higher fuel expenses, SkyWest has revised its full-year 2026 GAAP earnings per share expectation downwards to approximately $10.60, from a previous outlook of around $11. The company also provided a 2027 outlook, anticipating similar earnings per share despite modest block-hour growth. SkyWest continues to invest in its fleet, taking delivery of four E175 aircraft for United Airlines in Q3 and expecting seven more in Q4. The company has 63 E175 aircraft on firm order with Embraer, with plans to reach 300 E175 aircraft by the end of 2027.
Why It's Important?
SkyWest's Q3 earnings report highlights the dual pressures and opportunities facing regional airlines in the current economic climate. While strong demand for block hours from major airline partners like United, Delta, and American Airlines is boosting revenue and fleet expansion, the volatility and high cost of fuel remain a significant headwind. The downward revision of the 2026 EPS outlook underscores how sensitive airline profitability is to fuel prices, directly impacting investor expectations and stock performance. The company's strategic fleet investments, particularly in the E175 aircraft, signal a commitment to modernizing its fleet and meeting partner demands, which is crucial for long-term growth and operational efficiency. The flexibility in its Embraer order, allowing deferrals or terminations if partner assignments aren't secured, demonstrates a prudent approach to capital deployment in an uncertain market. Furthermore, SkyWest's consistent high completion rates and on-time performance, as noted by the Department of Transportation, are critical for maintaining partner confidence and passenger satisfaction, reinforcing its competitive position in the regional airline sector.
What's Next?
SkyWest anticipates continued fleet expansion, with plans to receive 18 E175s in 2027, primarily for Delta Air Lines, with the full production benefit expected in 2028. The company also intends to begin operating its first CRJ450 for United Airlines before the end of 2026, with potential for this opportunity to expand to 100 aircraft. Capital expenditures for 2027 are projected to be around $825 million, including significant investments in new E175 aircraft and CRJ fleet initiatives. Management expects capital spending to begin declining after 2027. The company will continue to monitor fuel costs, with its 2027 assumptions based on an average prorate fuel cost of $4.30 per gallon. Any significant deviation from this assumption could further impact future earnings. SkyWest's strategy will involve patient and disciplined market expansion for its prorate business, focusing only on accretive routes, while continuing to manage its debt, which has decreased by $1 billion since the end of 2022.
Beyond the Headlines
The challenges faced by SkyWest, particularly the impact of fuel costs on its prorate business, reflect broader economic trends affecting the entire airline industry. The company's decision to revise the estimated useful life of its E175 fleet from 22 to 30 years highlights a strategic adaptation to market realities, including sustained demand for the aircraft and contract extensions. This accounting change, which reduced depreciation expense, underscores how operational longevity and asset utilization are becoming increasingly critical for financial performance in capital-intensive industries. The ongoing investment in newer, more fuel-efficient aircraft like the E175, alongside the conversion of CRJ200s to CRJ450s, points to a long-term strategy of optimizing fleet composition for both efficiency and partner requirements. This approach is vital for regional carriers to remain competitive and profitable amidst fluctuating operational costs and evolving airline partnership dynamics, potentially setting a precedent for other regional operators facing similar pressures.