

What's Happening?
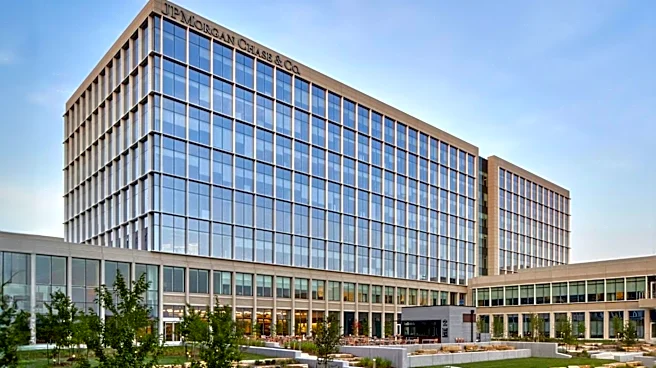
JPMorgan Chase & Co. filed its Quarterly Report on Form 10-Q with the SEC for the quarter ended September 30, 2026, on November 3, 2026. The financial services firm reported substantial figures, including $5.1 trillion in assets and $372 billion in stockholders’
equity as of the end of the third quarter. JPMorgan Chase operates globally through its Consumer & Community Banking, Commercial & Investment Bank, and Asset & Wealth Management segments, offering a comprehensive range of banking, payments, lending, and investment solutions. The company's shares experienced a marginal decline on October 13 after reporting Q3 2026 EPS of $5.57, which missed analyst estimates and marked its first quarterly profit miss since Q4 2023. This shortfall was attributed to weaker dealmaking and bond trading, with investment banking fees decreasing by 8% sequentially and fixed-income trading revenue falling 4% year-over-year. Despite these challenges, equity trading revenue surged by 49%, leading to an overall 15% increase in markets revenue. The bank also raised its full-year net interest income forecast to $106.2 billion, even as annual adjusted expense guidance rose to $108.6 billion.
Why It's Important?
The filing of JPMorgan Chase's Q3 2026 Form 10-Q provides critical insights into the health and performance of one of the largest financial institutions in the U.S. and globally. Its reported assets of $5.1 trillion and stockholders' equity of $372 billion underscore its significant role in the financial ecosystem. The mixed financial results, particularly the missed EPS estimates and declines in investment banking and fixed-income trading, highlight the impact of broader economic conditions such as market volatility, elevated interest rates, and economic uncertainty on the financial sector. While some areas like equity trading showed strength, the overall performance indicates a challenging environment for traditional banking activities. The raised full-year net interest income forecast suggests resilience in core lending operations, but the increased expense guidance points to ongoing operational costs. These financial indicators are closely watched by investors and analysts, influencing market sentiment and potentially affecting the broader U.S. economy due to JPMorgan Chase's systemic importance.
What's Next?
Analysts are closely monitoring JPMorgan Chase's performance, with expectations for the fiscal year ending December 2026 projecting an EPS growth of 17.8% year-over-year to $23.95. The company's earnings surprise history has been mixed, beating consensus estimates in three of the last four quarters but missing on one occasion. On October 15, Wells Fargo analyst Mike Mayo assigned JPMorgan Chase a "Buy" rating with a $390 price target, indicating a positive outlook from some financial experts. The mean price target from analysts is $368.60, representing a 9.1% premium to current price levels, with a Street-high target of $425 suggesting a potential upside of 25.8%. The consensus rating among 27 analysts is a "Moderate Buy," with 12 "Strong Buy" ratings, three "Moderate Buy," and 12 "Holds," a configuration that has remained stable over the past three months. Future performance will depend on the company's ability to navigate market volatility, manage expenses, and capitalize on growth opportunities in its diverse segments.
Beyond the Headlines
JPMorgan Chase's strategic focus on its various segments—Consumer & Community Banking, Commercial & Investment Bank, and Asset & Wealth Management—reflects a diversified approach to mitigating risks and capturing opportunities across different market conditions. The firm's ability to increase its full-year net interest income forecast despite a challenging quarter for investment banking suggests a robust underlying demand for its core banking services. However, the rise in adjusted expense guidance could signal ongoing investments in technology, compliance, or other operational areas necessary to maintain its competitive edge and meet regulatory requirements. The firm's global operations mean that its financial health has implications beyond the U.S., influencing international markets and financial stability. The continued scrutiny from analysts and the market will shape investor confidence and potentially impact the broader financial services industry's outlook.