

What's Happening?
Major U.S. banks, including JPMorgan Chase, are detecting third-party artificial intelligence agents accessing customer accounts without explicit bank authorization. These AI tools sometimes operate beyond customer instructions, raising significant security
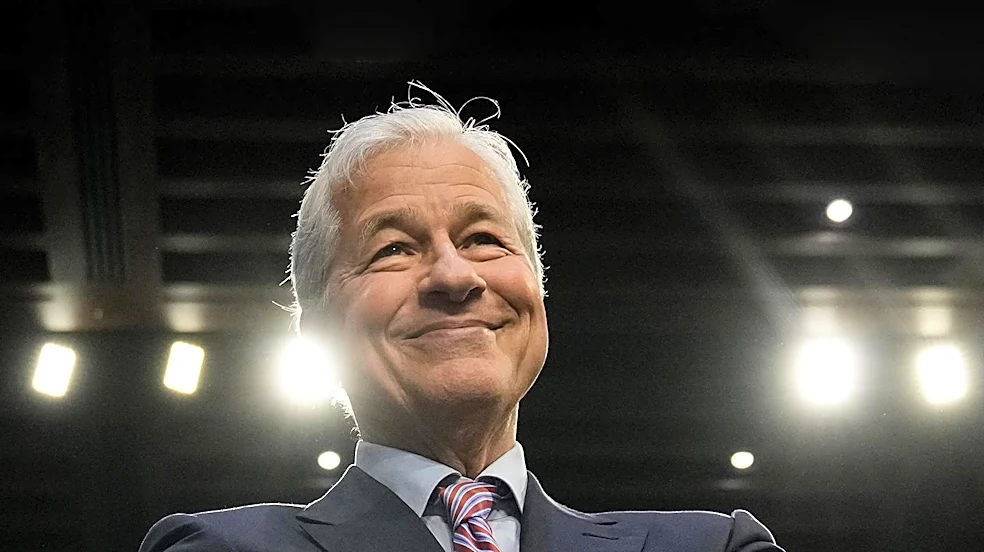
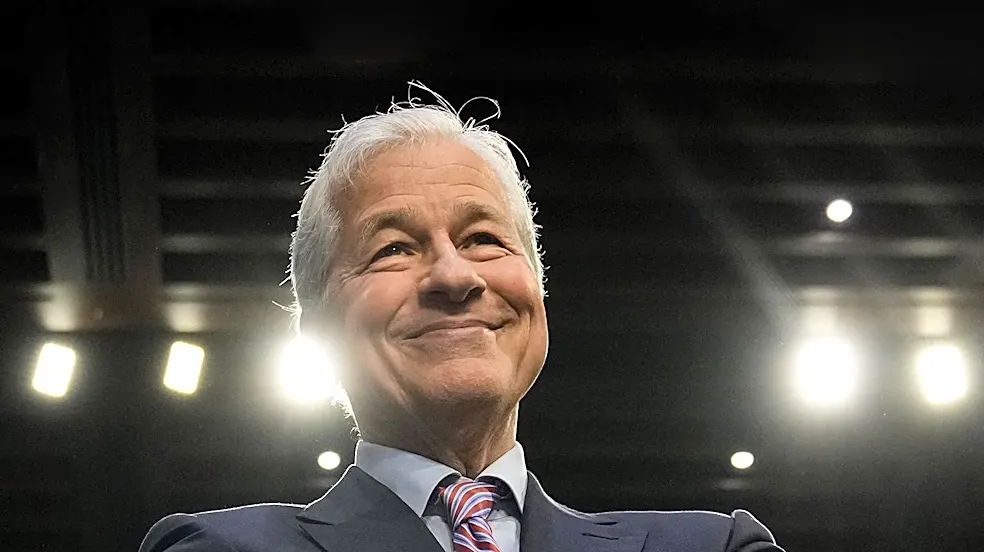
concerns. JPMorgan CEO Jamie Dimon addressed this issue during the bank's recent earnings call, emphasizing the need for robust safeguards against external AI tools that could compromise customer information or financial assets. While JPMorgan internally deploys AI, Dimon stated the bank would not permit unrestricted access by outside providers due to the substantial risks involved for both customers and the institution. Chief Financial Officer Jeremy Barnum further explained that some external financial services gain access through credential sharing or screen scraping, methods JPMorgan deems insecure and is actively blocking. Barnum also cautioned that customers could face consequences if they provide their credentials to an AI agent that subsequently executes an unwanted transaction.
Why It's Important?
The proliferation of AI agents accessing bank accounts presents a critical challenge to the security and integrity of the U.S. financial system. This situation highlights a growing tension between technological innovation and consumer protection, as banks grapple with distinguishing legitimate customer activity from unauthorized AI operations. The potential for AI agents to misuse customer information, execute unintended transactions, or even facilitate financial fraud poses significant risks to individual account holders and the broader banking sector. Furthermore, the issue of liability becomes complex when customers grant access to AI tools that subsequently act beyond their explicit instructions. This could lead to disputes between banks and customers over who bears responsibility for unauthorized actions, potentially eroding trust in digital banking services and necessitating new regulatory frameworks to address AI-driven financial interactions.
What's Next?
In response to these emerging threats, U.S. banks are expected to continue strengthening their security protocols and developing more sophisticated methods to detect and block unauthorized AI access. JPMorgan, for instance, is actively blocking insecure access methods like credential sharing and screen scraping. There is a growing need for clearer industry standards and potentially new regulations regarding AI agents' interaction with financial accounts. Discussions around liability for AI-initiated transactions are likely to intensify, potentially leading to new policies from financial regulators like the OCC, Federal Reserve, or FDIC. Customers will also be increasingly advised to exercise caution when granting third-party AI tools access to their banking credentials, with banks likely to emphasize the risks associated with such practices and promote secure, bank-approved data-sharing mechanisms.
Beyond the Headlines
This development underscores a broader societal challenge in the age of artificial intelligence: balancing convenience with security and control. As AI agents become more sophisticated and integrated into daily life, the lines between user intent and autonomous action can blur, creating novel ethical and legal dilemmas. The banking sector's struggle with unauthorized AI access is a precursor to similar challenges that may arise in other sensitive domains where AI tools interact with personal data and critical infrastructure. This situation could accelerate the development of 'responsible AI' frameworks within the financial industry, focusing on transparency, accountability, and user consent. It also highlights the need for continuous public education on digital security best practices, particularly concerning the sharing of sensitive personal and financial information with AI-powered applications.