
What's Happening?
Saudi Arabia is encountering significant challenges in its efforts to attract an estimated $100 billion in private credit investment, a key component of Crown Prince Mohammed bin Salman’s economic diversification plans. Despite the substantial opportunity,
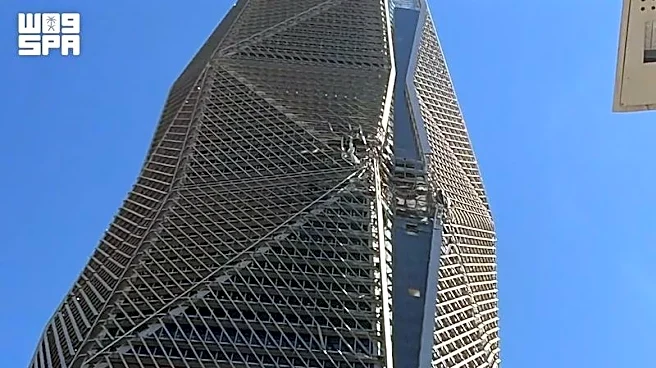
deploying capital at the necessary scale and speed is proving difficult. A recent $150 million financing deal for a Saudi firm, involving major international players like Goldman Sachs Group Inc. and HSBC Holdings Plc, took months to finalize due to regulatory delays, complex deal structures, and investor mix issues. This contrasts sharply with the weeks such a deal would typically take in other markets. The situation is further complicated by near-daily attacks from Houthis, which are impacting economic activity, exacerbating liquidity issues, and diminishing investor confidence. Fund managers also report increased difficulty in raising money from investors for local deals, with some backers preferring kingdom-based funds over international managers. Regulatory friction, including licensing processes that can take up to a year, and the additional costs of establishing local operations, are also impeding progress.
Why It's Important?
The struggles Saudi Arabia faces in attracting private credit are significant for its broader economic transformation goals. Crown Prince Mohammed bin Salman's Vision 2030 aims to diversify the economy away from oil dependence, requiring vast private investment across various sectors, including artificial intelligence. The current impediments, such as regulatory uncertainty and the slow flow of capital, directly threaten the realization of these ambitious plans. The difficulty in deploying capital, particularly into small and medium-sized businesses that are crucial for diversification but harder for foreign investors to assess, could stifle growth in key non-oil sectors. Furthermore, the ongoing Houthi attacks add a layer of geopolitical risk, making investors more cautious and potentially diverting capital to more stable regions. If Saudi Arabia cannot streamline its regulatory environment and mitigate perceived risks, it may struggle to secure the necessary private capital to fund its economic overhaul, impacting its long-term economic stability and global competitiveness.
What's Next?
To overcome these challenges, Saudi Arabia will likely need to address its regulatory framework to streamline licensing and operational setup for international fund managers. Simplifying deal structures and providing clearer guidelines could also encourage more foreign investment. The government may also need to enhance efforts to mitigate the impact of geopolitical tensions, such as the Houthi attacks, to restore investor confidence. Partnerships between international managers and local funds could become a more prevalent strategy, allowing Saudi firms to provide onshore structures and local market knowledge, while international partners contribute capital and underwriting expertise. Firms like Janus Henderson are still pursuing opportunities, with plans to close a $300 million fund, indicating that interest remains despite the hurdles. However, the focus might shift towards smaller transactions, which could be less attractive for larger global investors accustomed to deploying billions. The market is expected to evolve, with some experts predicting the Middle East could become a major private credit market within five to ten years, with an inflection point around 2027, provided these systemic issues are addressed.
Beyond the Headlines
The challenges in Saudi Arabia's private credit market highlight a broader tension between ambitious national development goals and the practicalities of attracting global capital. The situation underscores the importance of a robust and predictable regulatory environment, even for economies with significant potential. The preference among some investors for kingdom-based funds suggests a growing trend towards localization in investment, potentially driven by a desire for greater control, understanding of local nuances, or compliance with evolving regional policies. This could lead to a shift in how international firms engage with emerging markets, potentially requiring more localized partnerships and operational models. The higher potential returns (up to 16% or more) in Saudi Arabia, compared to more established markets, reflect the increased risk and effort involved, raising questions about the long-term sustainability of such premiums if underlying issues persist. This scenario also brings into focus the ethical considerations for investors operating in regions with geopolitical instability, balancing potential financial gains against broader societal and security concerns.