

What's Happening?
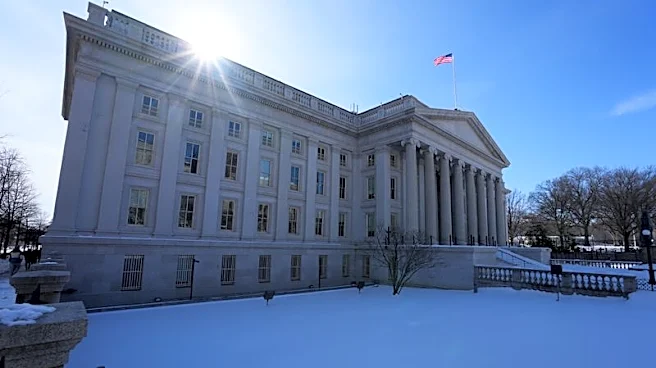
Treasury Secretary Scott Bessent is reportedly preparing for a significant restructuring of how the U.S. government issues debt, with expectations of a shift away from long-term bonds. This move is aimed at managing the nation's borrowing costs, which
have been under pressure. Wall Street analysts anticipate that the Treasury's quarterly refunding announcement could signal reductions in the sale of 20- and 30-year bonds starting in 2027, potentially offset by an increased reliance on Treasury bills and shorter-term notes. Some, like Citigroup, expect more immediate cuts to long-bond auctions. This potential policy reversal follows Bessent's earlier decision in August to expand Treasury bond buybacks after a surge in long-term yields, an intervention that surprised many market participants accustomed to the Treasury's traditional hands-off approach to influencing market interest rates through borrowing decisions. The federal government continues to face annual deficits of approximately $2 trillion, necessitating substantial and growing borrowing volumes. Thirty-year Treasury yields have remained above 5.30%, highlighting the persistent pressure on long-term borrowing costs.
Why It's Important?
This potential shift in U.S. debt issuance strategy carries significant implications for the broader economy and financial markets. By reducing the supply of long-duration bonds and increasing shorter-term debt, the Treasury aims to ease upward pressure on long-term yields. These yields directly influence critical borrowing costs, including mortgage rates, corporate financing, and other forms of credit, impacting consumers and businesses alike. A successful reduction in long-term yields could provide some relief to the housing market and stimulate corporate investment. However, this strategy also introduces new risks. Shorter-term debt requires more frequent refinancing, which could expose the government to greater volatility from future interest rate increases and sudden shifts in investor demand. The Treasury Borrowing Advisory Committee has already noted that Treasury bills account for approximately 22% of outstanding federal debt, exceeding the recommended 20% average for 2024. This increased reliance on short-term instruments could make the U.S. government's financing more susceptible to market fluctuations and investor sentiment, potentially leading to higher refinancing costs in the future.
What's Next?
The immediate focus will be on the Treasury's upcoming quarterly refunding announcement, which could provide definitive signals regarding changes in debt issuance strategy. While some analysts, like those at Citigroup, anticipate immediate cuts to long-bond auctions, others, such as UBS, expect changes in Treasury guidance rather than actual reductions in auction sizes before May. JPMorgan Chase strategists are more skeptical, predicting the Treasury will maintain existing guidance into 2027. Beyond the immediate announcement, market participants will closely monitor the effectiveness of any new strategies in managing long-term yields. The Treasury's expanded program for repurchasing outstanding long-term securities is also under scrutiny, with investors expecting the current $6 billion level for buyback operations to continue. The broader question remains whether the Treasury Department is moving away from its long-standing preference for predictable debt issuance towards a more flexible, market-responsive approach. This shift could signal a new era in how the U.S. finances its substantial debt, with potential ripple effects across global financial markets.
Beyond the Headlines
The potential overhaul of U.S. debt issuance reflects a deeper tension between managing immediate borrowing costs and ensuring long-term fiscal stability. While shifting to shorter-term debt might alleviate pressure on long-term yields in the near term, it does not reduce the overall amount of money the government needs to borrow. Instead, it alters the repayment timeline and reallocates interest rate risk. This strategy could lead to a situation of 'fiscal dominance,' where the sheer volume of government debt and deficits begins to constrain the Federal Reserve's ability to independently set monetary policy and control inflation. If monetary policy is forced to accommodate fiscal needs, it could undermine the Fed's credibility and its capacity to maintain price stability. The willingness of Treasury Secretary Bessent to depart from conventional approaches, such as expanding buybacks and intervening in foreign exchange markets to support the yen, suggests a more proactive and interventionist stance. This could set a precedent for future Treasury actions, potentially leading to a more dynamic, yet less predictable, approach to debt management. The long-term implications involve a delicate balancing act between market stability, fiscal responsibility, and the independence of monetary policy.