
What's Happening?
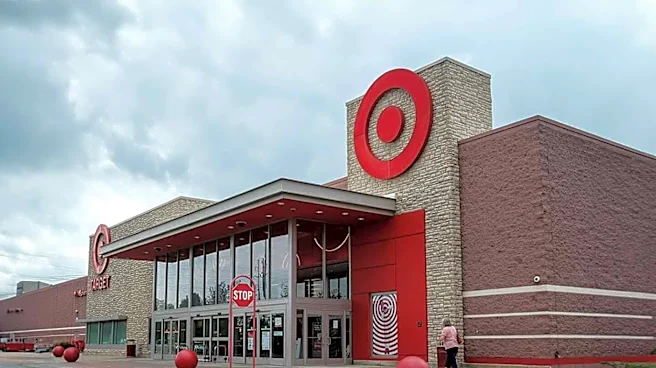
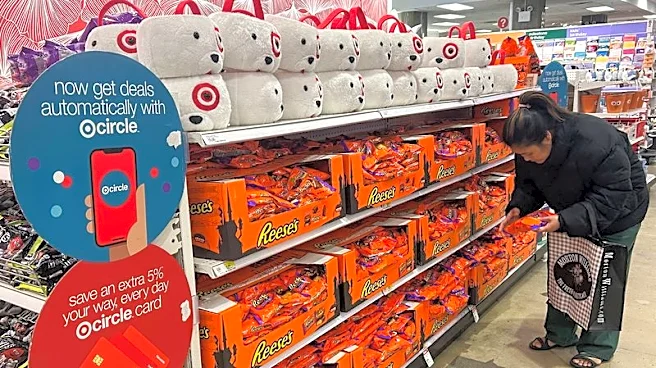
Target reported its third-quarter earnings on November 18, with revenue increasing by 7.1% to $27.1 billion. The company's earnings per share (EPS) reached $2.65, surpassing Wall Street estimates of $2.07 per share. A significant factor contributing to this
performance was a $301 million pretax tariff refund, which added $0.50 to the EPS. In the second quarter, tariff refunds had also contributed $1.65 per share to GAAP and adjusted earnings, and improved the operating income margin rate by 3.7%. Target's long-term debt and other borrowings decreased to $14.2 billion in Q3 2026, down from $15.4 billion in the prior-year period. The company's dividend appears to be well-supported, as it generates more cash and earnings than it distributes, with cash provided by operating activities reaching $4.5 billion in the first six months of 2026, compared to just over $1 billion paid in dividends.
Why It's Important?
Target's robust third-quarter performance, marked by increased revenue and earnings, demonstrates the company's resilience and operational efficiency within the competitive U.S. retail landscape. The significant impact of tariff refunds on both EPS and operating income margin highlights how external factors can substantially influence corporate profitability. While these refunds provide a temporary boost, the underlying strength of Target's core business, evidenced by its ability to generate substantial cash flow and reduce debt, is crucial for long-term investor confidence. For income-focused investors, Target's reliably supported dividend, with payouts well-covered by earnings and cash flow, makes it an attractive option. The company's financial health and strategic management of its balance sheet are key indicators for the broader retail sector's stability and potential for growth.
What's Next?
Target's future financial performance will depend on its ability to sustain strong results without the continued benefit of tariff refunds, which are not a permanent income source. The company will need to demonstrate ongoing improvements in its core operations to maintain its appeal as an income stock for long-term investors. Analysts and investors will be closely watching for strategies to drive organic growth and profitability in upcoming quarters. The retail giant's capacity to manage inventory, adapt to consumer spending trends, and optimize its supply chain will be critical. Continued reduction in long-term debt and consistent cash generation will also be key metrics for evaluating its financial health and dividend sustainability.
Beyond the Headlines
The reliance on tariff refunds to significantly boost earnings, while beneficial in the short term, underscores a broader vulnerability for U.S. companies to trade policies and their financial implications. This situation prompts a deeper look into how companies factor such unpredictable external windfalls into their long-term financial planning and investor communications. For Target, the challenge lies in transitioning from a period of tariff-related gains to demonstrating sustainable growth driven purely by operational excellence and market strategy. This scenario highlights the importance of diversified revenue streams and robust internal efficiencies to mitigate risks associated with fluctuating trade environments. The company's ability to navigate this transition will set a precedent for how other large retailers manage similar external financial influences.