

What's Happening?
Gen Z is currently carrying a higher debt load than Millennials did at the same age, even after adjusting for inflation, according to TransUnion data cited by credit counseling expert Ted Rossman of Money Management International. The nonprofit agency
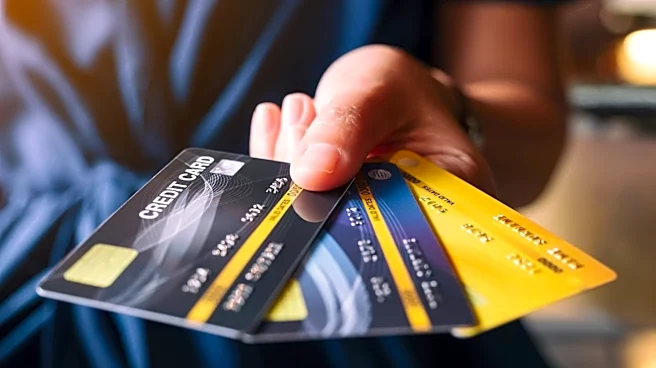
has observed a 35% increase in demand from Gen Z clients over the past year, with their debt loads rising by approximately 12% in the same period. This financial strain is attributed to factors such as student loans, high housing costs, and the prevalent use of 'buy now, pay later' (BNPL) services. Rossman emphasizes the importance of basic budgeting knowledge and caution regarding BNPL spending, highlighting that while these plans can offer interest-free periods, they still represent debt and require careful management to avoid overspending. He also warns about the high interest rates, often around 20%, associated with credit card debt.
Why It's Important?
This trend of increasing debt among Gen Z has significant implications for the U.S. economy and the financial well-being of a substantial portion of the younger workforce. High debt levels can hinder major life milestones such as homeownership, starting families, and long-term financial planning, potentially impacting consumer spending and economic growth. The reliance on BNPL services, while offering flexibility, can mask the true cost of purchases and lead to a cycle of debt if not managed responsibly. The rising demand for credit counseling services from Gen Z indicates a growing financial literacy gap or an inability to cope with current economic pressures, suggesting a need for more robust financial education and support systems for this demographic. The comparison to Millennials' debt at the same age underscores a worsening financial landscape for younger generations entering adulthood.
What's Next?
Financial experts like Ted Rossman are advising Gen Z to prioritize fundamental budgeting practices and to be acutely aware of the terms and potential interest rates associated with BNPL and credit card debt. There is an anticipated continued increase in demand for credit counseling services as more young adults grapple with their financial obligations. Educational initiatives focusing on responsible credit use, debt management, and the long-term implications of various payment options may become more critical. Additionally, as the holiday season approaches, there's a heightened concern about increased spending, with some Gen Z and Millennials planning to use AI for budgeting and gift idea generation, indicating a potential shift towards technology-assisted financial management to navigate these challenges.
Beyond the Headlines
The elevated debt burden on Gen Z reflects broader economic shifts, including rising costs of education and housing, which disproportionately affect younger generations. The normalization of BNPL services, often marketed as convenient payment solutions, may inadvertently contribute to a culture of instant gratification and delayed financial reckoning, potentially eroding traditional savings habits. This situation could lead to long-term societal impacts, including delayed economic independence for a significant demographic, increased financial stress, and potentially a widening wealth gap. The reliance on AI for financial planning, while innovative, also raises questions about data privacy and the potential for algorithmic biases in financial advice, highlighting a complex interplay between technology, personal finance, and societal well-being.