


What's Happening?
The Federal Reserve Board has finalized changes aimed at increasing the transparency and public accountability of its stress testing framework. These modifications are also intended to reduce volatility in the capital requirements linked to these stress tests.
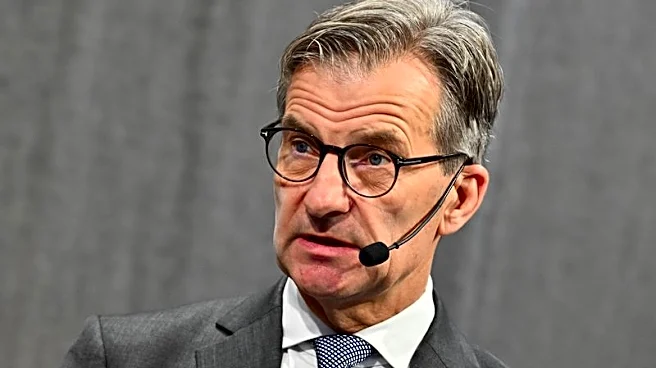
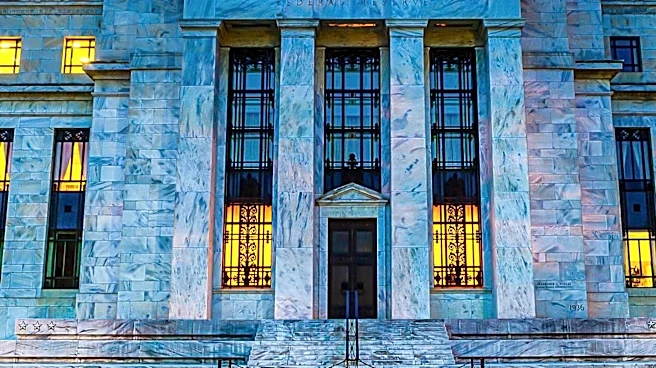
Governor Michael S. Barr noted that while he supports certain aspects of the new rule, such as using multiple scenarios for global market shock and considering the larger of the losses, he cannot fully endorse the final rule. Barr expressed concerns that the changes could diminish the dynamism, rigor, conservatism, and credibility of the stress tests over time, potentially undermining financial stability. He highlighted that disclosing stress test models and annual public comment processes on model changes and scenarios might make the tests less responsive to emerging risks and allow banks to optimize their balance sheets to the test rather than focusing on underlying risks. The Federal Reserve, established in 1913, serves as the central banking system of the United States, providing a safe, flexible, and stable monetary and financial system.
Why It's Important?
The Federal Reserve's stress tests are a critical tool for assessing the resilience of the U.S. financial system and ensuring that large banks can withstand adverse economic conditions. By enhancing transparency, the Fed aims to provide greater clarity to the public and financial institutions regarding how these tests are conducted and how capital requirements are determined. However, Governor Barr's dissent underscores a significant debate within the Federal Reserve regarding the balance between transparency and the effectiveness of regulatory tools. If the stress tests become less rigorous or credible, as Barr suggests, it could lead to a false sense of security within the financial system. Banks might focus on meeting the test's parameters rather than genuinely mitigating underlying risks, potentially increasing concentrated risks, similar to issues observed during the Global Financial Crisis. This could impact the stability of the U.S. economy by making banks more vulnerable to unforeseen shocks, ultimately affecting consumers, businesses, and investors.
What's Next?
The implementation of the finalized rule will likely lead to increased public scrutiny and discussion regarding the effectiveness of the Federal Reserve's stress testing framework. Financial institutions will need to adapt their strategies to the new transparency requirements and potentially revised capital calculations. Governor Barr's concerns suggest that there may be ongoing internal debates within the Federal Reserve about the long-term implications of these changes. Future economic conditions and any emerging financial vulnerabilities will serve as real-world tests of the new framework's efficacy. Stakeholders, including financial analysts, economists, and policymakers, will closely monitor how these changes affect bank behavior, risk management practices, and overall financial stability. The Federal Reserve may also face continued pressure to refine its stress testing methodologies to address any perceived weaknesses or unintended consequences arising from the new rule.
Beyond the Headlines
The debate surrounding the Federal Reserve's stress test modifications highlights a fundamental tension in financial regulation: the need for transparency and accountability versus the imperative to maintain robust and adaptable oversight. While increased transparency can foster public trust and reduce information asymmetry, it also risks creating a 'teach to the test' environment where regulated entities optimize for disclosed metrics rather than addressing the full spectrum of potential risks. Governor Barr's warning about 'calcified models' and the potential for increased concentrated risks points to a deeper systemic issue where regulatory frameworks, if not carefully designed and continuously updated, can inadvertently create new vulnerabilities. This situation underscores the complex challenge of designing regulations that are both predictable and flexible enough to respond to an evolving financial landscape, ultimately impacting the long-term health and stability of the U.S. financial system and its ability to support economic growth.