
What's Happening?
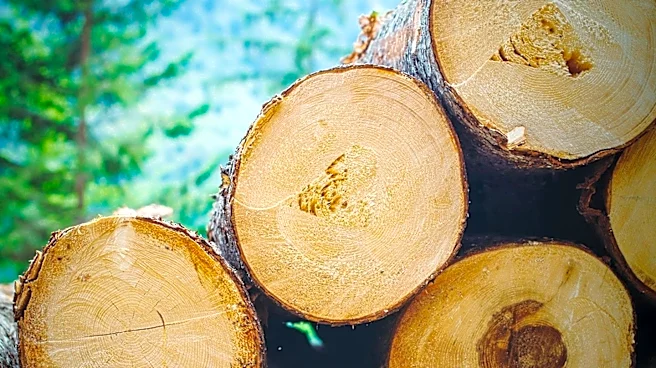
Southern states have emerged as the dominant force in U.S. timber production over the past three decades, with Mississippi harvesting nearly 14.8 million MCF (thousand cubic feet) of timber between 1993 and 2024. This shift in the timber industry's center
of gravity from the Pacific Northwest to the South occurred after federal harvests in Oregon and Washington sharply declined in the 1990s due to the Northwest Forest Plan. By 2011, the South accounted for 63 percent of all timber harvested in the United States, according to the U.S. Forest Service. Georgia leads the nation in total timber production, followed by Alabama and Mississippi. Oregon remains the top-ranking state outside the Southeast, harvesting approximately 10.72 million MCF of roundwood during the same period, primarily Douglas-fir. While Southern states often prioritize pulpwood for paper and packaging, Oregon's timber industry is heavily focused on softwood sawlogs for lumber and plywood.
Why It's Important?
The geographical shift in U.S. timber production has significant economic and environmental implications. The dominance of Southern states, characterized by fast-growing pine forests and privately owned lands, highlights a different forestry model compared to the Pacific Northwest, where federal land management and environmental regulations have played a larger role. This shift impacts regional economies, employment in the timber industry, and the types of wood products manufactured. Southern states' focus on pulpwood supports paper and packaging industries, while Oregon's emphasis on sawlogs underpins lumber and plywood production. The decline in federal harvests in the Pacific Northwest has led to controversies over logging policies, as seen in Oregon's current debates over ballot measures. Understanding these regional differences is crucial for policymakers, industry stakeholders, and environmental groups as they navigate issues of sustainable forestry, economic development, and conservation across the nation.
What's Next?
The trend of Southern states leading U.S. timber production is expected to continue, driven by their managed pine forests and private land ownership. However, ongoing debates and legal challenges, particularly in states like Oregon, regarding logging policies and environmental regulations, could influence future timber harvests and industry practices. The U.S. timber logistics market is projected to grow, facing challenges such as a shortage of qualified log truck drivers and increasing digital chain-of-custody requirements. This growth is anticipated to be fueled by expanding engineered wood applications and intermodal freight solutions. The industry will likely continue to adapt to market demands, technological advancements, and evolving environmental standards, potentially leading to further innovations in sustainable forestry and wood product manufacturing across different regions of the U.S.
Beyond the Headlines
The evolution of the U.S. timber industry reflects broader changes in land use, environmental policy, and global markets. The shift from the Pacific Northwest to the South underscores the impact of federal regulations, such as the Northwest Forest Plan, on regional economies and ecosystems. It also highlights the varying approaches to forest management, from intensive plantation forestry in the South to more complex, multi-use management on federal lands. The ongoing challenges in timber logistics, including labor shortages and digital requirements, point to the need for modernization and efficiency in the supply chain. Furthermore, the increasing demand for engineered wood applications suggests a move towards more sustainable and efficient use of timber resources. This dynamic landscape necessitates continuous adaptation from the industry and thoughtful policymaking to balance economic interests with ecological conservation and community well-being.