

What's Happening?
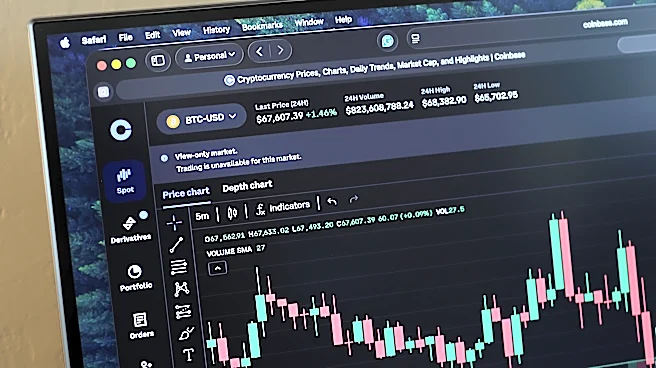
Coinbase Global Inc. announced on Monday that its Coinbase National Trust Company has received full authorization from the Office of the Comptroller of the Currency (OCC), effective November 6. This elevates its conditional approval from April 2 into
a fully chartered institution, placing Coinbase's institutional digital-asset custody operations under direct federal banking supervision. This federal trust charter allows Coinbase to provide specialized custody and fiduciary services, but it does not permit traditional commercial banking activities such as consumer deposits or lending. Assets held by the trust company are not FDIC-insured. Concurrently, PNC Bank is expanding its partnership with Coinbase by piloting USDC stablecoin payments for eligible corporate and institutional clients. This initiative allows businesses to receive Circle's dollar-pegged USDC, which is automatically converted into U.S. dollars, aiming for faster settlement and improved access to funds, particularly for international transactions.
Why It's Important?
The OCC's full approval of Coinbase National Trust Company marks a significant regulatory milestone for the cryptocurrency industry in the U.S., providing a clearer and more standardized federal framework for digital asset custody. This move could enhance institutional confidence in holding digital assets, potentially attracting more traditional financial firms into the crypto space. For Coinbase, it streamlines regulatory arrangements for institutional clients and solidifies its position as a leading crypto custodian. The expanded partnership with PNC Bank further bridges the gap between traditional banking and blockchain technology, demonstrating a practical application of stablecoins for corporate payments. This pilot could pave the way for broader adoption of stablecoins in business transactions, offering benefits like faster, 24/7 settlement and reduced costs, thereby impacting U.S. financial infrastructure and payment systems. However, the lack of FDIC insurance for assets held by the trust company highlights ongoing regulatory distinctions and potential risks for institutional clients.
What's Next?
Coinbase's institutional custody business is slated to transition to the newly chartered national trust entity over a three-year period. While the federal charter provides a nationwide supervisory framework, Coinbase's other services, such as trading, staking, and financing, will continue to be offered by its other affiliates. The PNC Bank pilot program will focus on testing and learning the benefits of stablecoin features for corporate clients, with potential for broader implementation if successful. The expansion of federal charters for crypto firms remains a contentious issue, with groups like the Independent Community Bankers of America challenging the OCC's authority in court. This legal challenge could influence future regulatory decisions and the pace of crypto integration into the traditional banking system. Despite these positive regulatory and partnership developments, Coinbase's stock performance has been challenging, indicating that market confidence in its financial returns is still evolving.
Beyond the Headlines
The federal trust approval for Coinbase and its expanded stablecoin partnership with PNC Bank signal a gradual but significant institutionalization of cryptocurrency in the U.S. financial landscape. This development moves beyond mere speculative trading of digital assets towards their functional integration into core financial services. The distinction between a trust company and a commercial bank, while legally clear, highlights the ongoing regulatory struggle to categorize and govern novel financial technologies. This could lead to a more nuanced regulatory environment where different aspects of crypto businesses are overseen by various agencies, potentially creating a complex compliance landscape. Furthermore, the use of stablecoins for corporate payments, while offering efficiency, also raises questions about monetary policy, financial stability, and the role of central banks in a world with private digital currencies. This evolution could accelerate the debate around a potential U.S. central bank digital currency (CBDC) and its implications for the existing financial ecosystem.