
What's Happening?
Retiring in Portugal for Americans in 2027 will involve significant changes compared to previous years, primarily due to shifts in tax policies and housing costs. The Non-Habitual Resident (NHR) tax regime, which offered a flat 10% tax on foreign pensions,
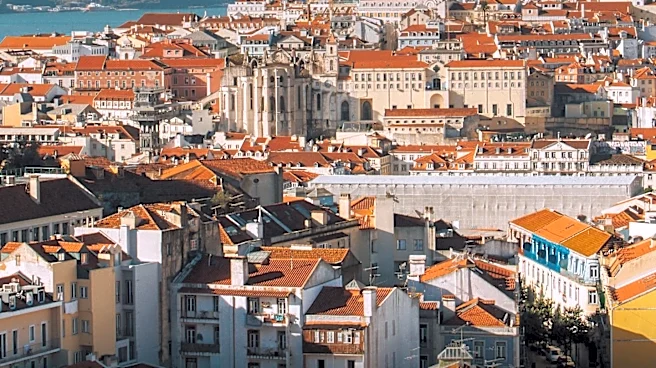
was repealed on January 1, 2024, meaning new retirees will face standard progressive income tax rates ranging from 13% to 48%. Housing costs have also polarized, with rental rates in prime areas like Lisbon, Cascais, Porto, and the Algarve surging, while inland towns remain more affordable. The D7 Passive Income Visa remains the primary pathway for American retirees, with minimum income requirements tied to Portugal’s national minimum wage, projected to be at least €970 per month (approximately $1,096 USD) for a single retiree in 2027. Retirees must also secure private health insurance for visa entry and fund a local Portuguese bank account with significant savings.
Why It's Important?
These changes significantly impact U.S. citizens considering retirement in Portugal, altering the financial viability and planning required for such a move. The repeal of the NHR tax regime means that the tax benefits that once made Portugal highly attractive are largely gone, requiring retirees to factor in higher tax liabilities on their U.S. Social Security, 401(k), and IRA distributions. This shift could make Portugal less financially appealing for some, potentially redirecting U.S. retirees to other countries with more favorable tax policies. The rising housing costs in popular regions also mean that the dream of an affordable European retirement might be harder to achieve in prime locations, pushing retirees towards less developed areas or requiring a higher retirement budget. These factors necessitate a more rigorous financial assessment and potentially a re-evaluation of retirement destinations for many Americans.
What's Next?
U.S. retirees planning to move to Portugal will need to undertake comprehensive financial modeling to understand their net spendable income after Portuguese progressive income taxes. It will be crucial to obtain a Portuguese NIF (tax identification number), open a local bank account, and secure a 12-month registered lease before applying for the D7 visa. Given the changes, professional tax advice from cross-border specialists is essential to navigate the new tax landscape and avoid unexpected financial burdens. Retirees should also carefully consider their preferred region within Portugal, balancing lifestyle desires with the varying costs of living. The administrative pace and potential backlogs with Portugal’s immigration agency (AIMA) also mean that applicants should anticipate scheduling delays and administrative friction during the residency process.
Beyond the Headlines
The evolving retirement landscape in Portugal for U.S. citizens reflects broader trends in international migration and the impact of global economic shifts on local policies. The repeal of the NHR regime, while impacting foreign retirees, is part of a larger effort by Portugal to address its own housing crisis and ensure tax equity for its residents. This highlights the delicate balance governments face between attracting foreign investment and talent, and protecting the interests of their local populations. The challenges faced by U.S. retirees in Portugal also underscore the complexities of international retirement planning, including navigating different legal systems, healthcare access, and currency fluctuations. It encourages a more nuanced understanding of the 'expat dream,' revealing that even seemingly idyllic retirement destinations come with their own set of economic and administrative realities that require careful consideration and adaptation.