

What's Happening?
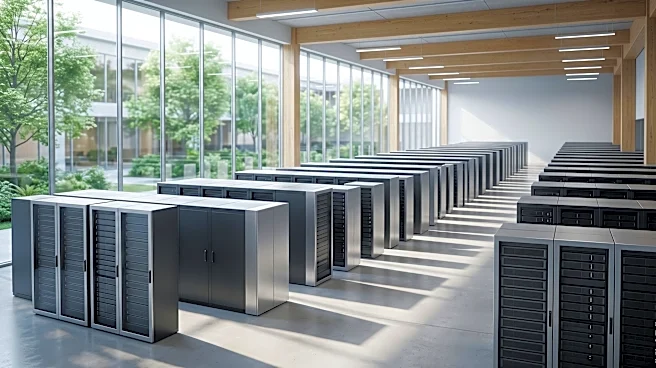
Meta is under scrutiny from the U.S. Internal Revenue Service (IRS) for classifying some of its AI data centers as 'experimental facilities.' This designation allows companies to claim tax credits on equipment purchased for research and development, which
are intended to incentivize innovation. According to The New York Times, Meta's use of this classification has enabled the company to save billions on its tax bill. Specifically, Meta cut its 2024 tax bill by $2 billion and is projected to save $3.9 billion in 2025, totaling nearly $6 billion in tax savings over two years. The report indicates that Meta is the largest claimant of this particular tax credit, and its auditor, EY, approved this approach, even suggesting other companies adopt it. Meta's AI data centers are designated as 'pilot models,' distinct from its regular data centers used for cloud computing and storage services.
Why It's Important?
This situation highlights a significant point of contention between large technology companies and tax authorities regarding the interpretation and application of tax incentives. The 'experimental' designation is designed for projects with a risk of failure, not standard business operations. Meta's substantial tax savings, amounting to billions, raise questions about the fairness and intent of such tax credits, especially when applied to facilities that are integral to its core business expansion into AI. The IRS's scrutiny could lead to a re-evaluation of how these tax credits are granted and utilized across the tech industry, potentially impacting other companies that have adopted similar strategies. The Joint Committee on Taxation estimates that these experimental tax credits will cost the U.S. government $32.1 billion in 2025, with Meta's claims representing approximately 10% of that total. This controversy also underscores the broader debate about corporate tax avoidance and the financial responsibilities of highly profitable technology giants.
What's Next?
Meta's classification of its AI data centers as 'experimental' is likely to face continued scrutiny from the IRS. The company's reserve for potential tax challenges has increased significantly, indicating an awareness of the risk. This situation could lead to formal challenges from the IRS, potentially resulting in Meta owing back taxes and penalties. The outcome of this dispute could set a precedent for how other technology companies classify their AI infrastructure for tax purposes. It may also prompt legislative review of the research and development tax credit program to clarify its scope and prevent its application to what some might consider standard commercial operations. Other companies that have followed EY's advice to adopt similar tax strategies may also face increased scrutiny. This issue could also fuel public and political debate about corporate tax policies and the need for greater transparency in how large corporations utilize tax incentives.
Beyond the Headlines
The controversy surrounding Meta's tax credits for its 'experimental' AI data centers delves into the complex interplay between corporate innovation, tax policy, and public finance. While tax incentives are designed to foster technological advancement, their application to massive, commercially driven AI infrastructure raises ethical questions about whether these benefits are being used as intended or as a means of significant tax reduction. The designation of AI data centers as 'pilot models' suggests a strategic interpretation of tax law, potentially blurring the lines between genuine experimental research and large-scale commercial deployment. This situation could erode public trust in the fairness of the tax system and intensify calls for stricter regulations on corporate tax practices. Furthermore, it highlights the immense financial power of tech giants and their ability to leverage legal frameworks to their advantage, potentially at the expense of public revenue that could fund other critical services. The long-term implications could include a re-evaluation of tax incentives for emerging technologies, aiming to balance innovation with equitable tax contributions.