

What's Happening?
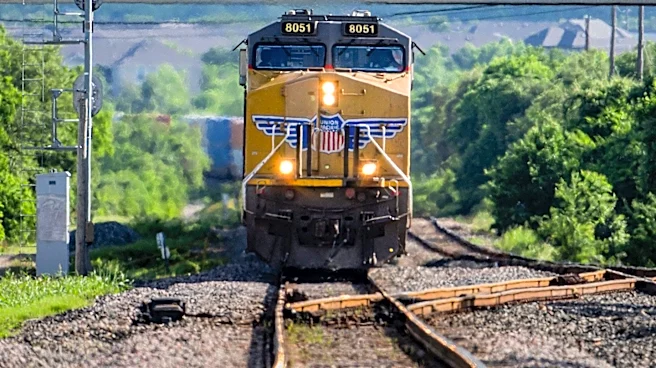
Union Pacific (UNP) shares recently closed at US$304.0, following a strong multi-year performance. This has prompted questions among investors regarding whether the current stock price aligns with the railroad's expected future cash flows, particularly
from a Discounted Cash Flow (DCF) perspective. Over the past three years, Union Pacific has delivered a 53.1% share price return, placing significant expectations on its future cash generation. The company's ability to convert freight revenue into consistent free cash flow is a key factor influencing investor support for its current market value. While the latest twelve-month free cash flow is approximately $6.6 billion, DCF projections suggest that the estimated intrinsic value is below the current share price, indicating that the market may be paying a full price for these cash flows.
Why It's Important?
The debate over Union Pacific's valuation is critical for investors, as it determines whether the stock offers a compelling investment opportunity or is potentially overvalued. The discrepancy between the current share price and the DCF-derived intrinsic value suggests that the market might be pricing in optimistic future growth or other factors not fully captured by cash flow projections. Union Pacific's consistent free cash flow generation is a strong indicator of its operational efficiency and financial stability as a mature freight network. However, if future cash flows do not meet market expectations, the stock could be vulnerable to a correction. The company's ability to maintain its freight revenue and manage costs will be crucial in justifying its current premium valuation.
What's Next?
The future movement of Union Pacific's stock will largely depend on whether its actual cash flows align with market expectations and intrinsic value estimates. Investors will closely monitor the company's financial performance, particularly its ability to sustain and grow free cash flow. Any changes in freight demand, operational costs, or capital needs could significantly impact its valuation. The market will also consider various narratives, such as a proposed merger with Norfolk Southern, which could introduce substantial revenue and cost synergies, potentially justifying a higher valuation. Before making investment decisions, stakeholders will need to assess the company's leadership and executive compensation to ensure alignment with shareholder interests.
Beyond the Headlines
Union Pacific's valuation dilemma reflects a broader challenge in financial markets: reconciling strong historical performance and current market price with fundamental intrinsic value. The concept of a 'premium to cash flow' suggests that investors are willing to pay more for the stock than its discounted future cash flows might strictly dictate, often due to growth narratives, market sentiment, or strategic opportunities like potential mergers. This situation highlights the subjective nature of valuation and the influence of qualitative factors on investor decisions. It also underscores the importance of considering multiple valuation metrics and narratives, as a single model may not fully capture a company's complex financial reality and future potential. The interplay between quantitative analysis and market perception is a constant dynamic in stock market performance.