


What's Happening?
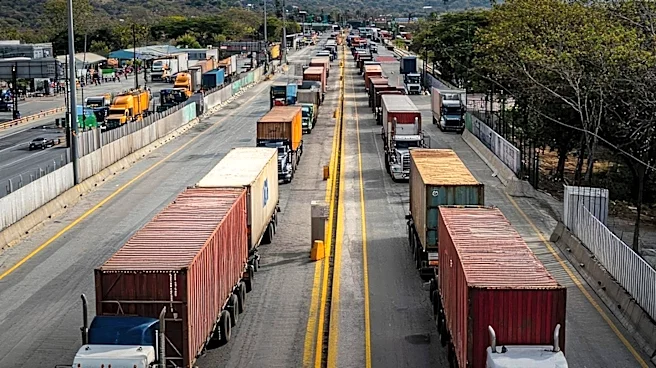
U.S. truck tonnage experienced another month of declines in August, according to data released by the American Trucking Associations (ATA). The advanced seasonally-adjusted For-Hire Truck Tonnage Index fell by 0.5% in August, following a 1% decline in July.
This marks a 1.6% decrease annually in August, steeper than the 0.7% annual decline in July. On a year-to-date basis, the advanced seasonally-adjusted tonnage is up 1% annually, primarily due to robust gains earlier in the year from February through April. ATA Chief Economist Bob Costello stated that the truck market has 'flipped' this year, with recent tonnage levels confirming that the declines are due to reduced capacity rather than strong demand. Truck tonnage has been down in four of the last five months and has fallen 4.3% from its recent peak in March.
Why It's Important?
The continued decline in truck tonnage, despite a year-to-date gain, signals a complex and challenging environment for the U.S. trucking industry. While the market is generally better due to supply constraints, the underlying issue of reduced capacity, rather than robust demand, indicates potential inefficiencies or structural shifts within the logistics sector. This trend can impact supply chains, potentially leading to higher shipping costs for businesses and, consequently, higher prices for consumers. The trucking industry is a critical component of the U.S. economy, responsible for moving a vast majority of goods. Fluctuations in tonnage levels can serve as an indicator of broader economic health, suggesting that while some sectors may be recovering, the movement of goods is still facing headwinds. The 'flipping' of the truck market implies a significant change in dynamics that requires careful monitoring by businesses and policymakers.
What's Next?
The trucking industry will likely continue to grapple with capacity issues and their impact on tonnage levels. Businesses reliant on freight transportation should anticipate potential volatility in shipping costs and delivery times. Industry stakeholders, including the ATA, will likely continue to analyze these trends to understand the long-term implications for supply chain management and economic stability. Efforts to address capacity constraints, whether through driver recruitment, fleet modernization, or infrastructure improvements, may become more urgent. The performance of the trucking sector will remain a key economic indicator, influencing investment decisions and policy discussions related to logistics and transportation infrastructure in the U.S. The coming months will reveal whether the market stabilizes or if further adjustments are needed to balance capacity with demand.
Beyond the Headlines
The distinction between tonnage declines due to reduced capacity versus weak demand is crucial for understanding the health of the U.S. economy. If the issue is primarily capacity, it points to challenges within the labor market (e.g., driver shortages) or operational constraints (e.g., fleet availability, regulatory hurdles). This suggests that even if consumer demand were to increase, the ability to move goods efficiently might still be hampered, leading to bottlenecks and inflationary pressures. Conversely, if demand were the primary issue, it would signal a broader economic slowdown. The current scenario, leaning towards capacity constraints, highlights the need for strategic investments in the trucking workforce and infrastructure to ensure the resilience and efficiency of the national supply chain, irrespective of demand fluctuations. This could also accelerate the adoption of automation and new technologies to mitigate labor-related capacity issues.