
What's Happening?
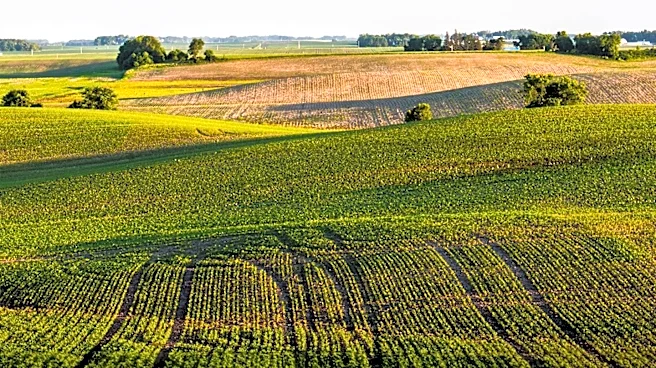
New research from Purdue University indicates that the historical price advantage for Brazilian farmland over Iowa farmland has widened again, following a period where the gap had significantly narrowed. Joana Colussi, a research assistant professor at Purdue University,
compared farmland values in Iowa with those in Mato Grosso, Brazil's largest soybean-producing state. Both regions have experienced substantial land value increases since 2002. Iowa's average farmland value rose from approximately $2,100 per acre in 2002 to around $11,500 per acre by 2025. Mato Grosso saw its values increase from about $1,300 per acre in 2002, with particularly sharp rises between 2010-2014 and 2020-2022, bringing its values close to Iowa's. However, recent market conditions, including declining soybean and corn prices, have impacted both countries. Iowa farmland values have remained relatively stable, while values in Mato Grosso have declined, resulting in Iowa farmland being valued 27 percent higher than comparable land in Mato Grosso by 2025. Both Brazilian and Iowa producers face financial pressures from declining farm revenues, rising input costs, and tighter profit margins, yet farmland values in both regions remain historically high.
Why It's Important?
This widening price gap has significant implications for the global agricultural market and the competitiveness of U.S. soybean producers. Historically, lower farmland costs in Brazil provided a competitive edge against Iowa farmers. As this advantage diminishes or reverses, it could alter the cost structures for soybean production, potentially impacting global supply dynamics and trade flows. For Iowa soybean producers, the increased relative value of their land, while indicating strong asset appreciation, also means higher capital costs for expansion compared to their Brazilian counterparts. This situation highlights the complex interplay of global commodity prices, local economic conditions, and land market dynamics. The stability of Iowa's farmland values amidst global pressures suggests a robust underlying demand or limited supply, which could be influenced by factors like investor interest or domestic agricultural policies. Conversely, the decline in Brazilian values reflects greater sensitivity to commodity price fluctuations and other financial pressures in that market.
What's Next?
Looking ahead, the trajectory of commodity prices will be a critical factor. Colussi suggests that improving commodity prices could provide support for Brazilian farmland markets, potentially leading to an improvement in conditions by 2027. For Iowa and the broader U.S., the outlook for farmland values remains relatively stable, with values expected to change little as markets adjust to lower crop prices, high production costs, and elevated interest rates. The Purdue University/CME Group Ag Economy Barometer's Long-Term Farmland Value Expectations Index, which remains above pre-2020 levels, supports a positive longer-term outlook despite current pressures. Farmers in both regions will continue to focus on managing costs and maintaining profitability to navigate these changing economic landscapes. The evolving farmland value differential will likely influence investment decisions, land acquisition strategies, and overall competitiveness in the international soybean market.
Beyond the Headlines
The fluctuating farmland price gap between Iowa and Brazil underscores the interconnectedness of global agricultural economies and the vulnerability of local markets to international forces. Beyond direct economic impacts, this trend could influence agricultural policy discussions in both countries, particularly regarding land ownership, subsidies, and trade agreements. The stability of U.S. farmland values, even amidst challenges, might reflect a perception of greater long-term security or investment appeal compared to emerging markets. Conversely, the volatility in Brazilian values could prompt discussions about risk management and diversification strategies for agricultural investors there. This situation also highlights the broader theme of land as a critical, finite resource whose value is shaped by a complex web of economic, geopolitical, and environmental factors, influencing not just agricultural production but also national wealth and food security strategies.