

What's Happening?
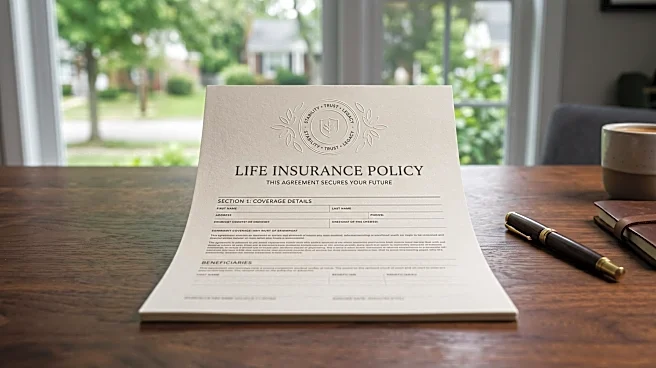
Many Americans, particularly younger adults, significantly overestimate the cost of life insurance, a perception that acts as a major barrier to obtaining adequate coverage. According to a survey by LIMRA and Life Happens, adults aged 18 to 30 believe
life insurance costs approximately ten times more than its actual price. This misconception contributes to a situation where many families lack sufficient financial protection. For instance, 48% of millennials and 39% of Gen Z respondents cited perceived cost as a reason for not owning life insurance or having insufficient coverage. The issue is compounded by a lack of understanding regarding how life insurance functions, with less than a quarter of young adults feeling knowledgeable about underwriting processes. Despite this knowledge gap, over half of young adults who admitted to not fully understanding life insurance still recognized their need for it. The cost of life insurance is influenced by factors such as age, gender, medical history, smoking status, occupation, and the policy's payout amount. Term insurance policies are generally more affordable, ranging from $15 to $100 per month, while whole life policies can cost several hundred dollars monthly due to lifelong coverage and cash value accumulation.
Why It's Important?
This widespread overestimation of life insurance costs has significant implications for U.S. families and the broader financial security landscape. When individuals are underinsured or lack life insurance entirely, their dependents face substantial financial vulnerability in the event of an unexpected death. This can lead to difficulties covering essential expenses like mortgages, debts, and educational costs, potentially pushing families into financial distress. The reluctance to purchase adequate coverage, driven by cost misconceptions, undermines the primary purpose of life insurance as a safety net. Furthermore, the educational gap regarding life insurance underwriting and policy types suggests a broader issue in financial literacy among younger generations. This lack of understanding can prevent individuals from making informed decisions about their financial planning, impacting their ability to secure their future and the well-being of their loved ones. The disparity between perceived and actual costs also highlights a challenge for the insurance industry in effectively communicating the value and affordability of its products to potential customers.
What's Next?
To address the issue of underinsurance due to cost overestimation, financial planners and insurance providers will likely need to enhance their educational outreach. Strategies could include providing clearer, more accessible information about the actual costs of various life insurance policies and demystifying the underwriting process. Encouraging individuals to obtain multiple quotes from reputable carriers could help them see the real numbers and dispel assumptions about high costs. Additionally, emphasizing the importance of assessing individual needs, especially after major life events like buying a home or having children, will be crucial. This involves guiding consumers to understand whether a term policy, which focuses on income replacement for a specific period, or a permanent policy, offering lifelong coverage and cash value, best suits their financial goals. The industry may also explore more transparent pricing models and simplified policy explanations to bridge the knowledge gap and encourage greater adoption of life insurance among younger demographics.
Beyond the Headlines
The phenomenon of overestimating life insurance costs points to deeper psychological and behavioral economic factors at play. People often rely on heuristics or mental shortcuts when estimating costs, which can lead to significant biases, especially for complex financial products like insurance. This 'perception gap' is not merely about a lack of information but also about how information is processed and perceived. The long-term implications extend beyond individual financial security to societal resilience. A population that is broadly underinsured can place greater strain on social safety nets and public assistance programs when unexpected tragedies occur. Ethically, there's a responsibility for the financial industry to ensure that essential protective products are understood and accessible, rather than being perceived as prohibitively expensive. Culturally, there might be a need to shift narratives around financial planning to emphasize proactive protection rather than reactive crisis management, fostering a greater appreciation for the role of insurance in overall well-being.