

What's Happening?
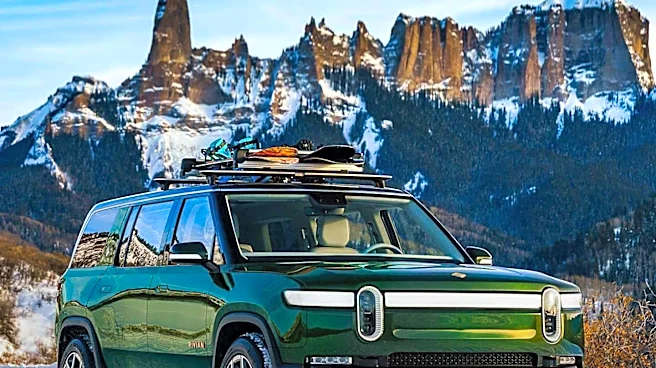
Rivian Automotive's stock has fallen to US$13.54, a significant drop from US$19.71 at the start of the period, resulting in a 30.2% decline for investors this year. This downturn comes despite a recent boost from Volkswagen, which increased its stake
in Rivian to 15.9% and provided a US$1 billion term loan. The company's quarterly figures showed revenue reaching US$2,155 million and a narrowed loss of US$913 million, with net margin improving from -75.3% to -42.4%. However, profitability remains unproven, leading to ongoing debate among investors about the company's financial viability. Analysts are divided, with some seeing a Fair Value of US$21.83 based on potential cost savings from the R2 platform and new software revenue streams, while others are more cautious, setting a Fair Value of US$14.04 due to high expenses and cash burn.
Why It's Important?
The performance of Rivian Automotive is a key indicator for the broader electric vehicle (EV) market and its investment landscape in the U.S. The company's struggle to achieve profitability, despite significant revenue growth and strategic partnerships like the one with Volkswagen, highlights the challenges faced by EV startups in scaling production and managing high operational costs. This situation impacts not only Rivian's investors, who have seen substantial losses, but also potential investors in the EV sector, who may become more wary of the long road to profitability. The debate over Rivian's ability to convert partnerships and software features into sustainable income streams alongside vehicle gross profit underscores the evolving business models within the automotive industry, moving beyond traditional manufacturing to include technology and services.
What's Next?
For Rivian, the immediate future will likely involve continued efforts to demonstrate the financial benefits of its R2 platform and in-house software. The company will need to show that its partnerships and autonomy features can translate into material software and licensing income, alongside improved vehicle gross profit, to justify a higher valuation. Investors will be closely monitoring future quarterly reports for signs of sustained margin improvement and a clearer path to profitability. The success of these initiatives will be crucial in determining whether outside capital is effectively buying time for the company to mature or merely slowing the rate of cash burn. The market's perception of Rivian's long-term viability will heavily depend on its ability to execute on these strategic goals and reduce its reliance on external funding.
Beyond the Headlines
The challenges faced by Rivian Automotive extend beyond its immediate financial performance, touching upon the broader narrative of innovation versus profitability in the U.S. tech and automotive sectors. The company's journey reflects the high-stakes environment for startups aiming to disrupt established industries, where significant capital investment is required upfront, and the path to sustainable returns can be long and uncertain. This situation also raises questions about investor patience and the metrics used to evaluate growth companies, particularly those in capital-intensive sectors like EV manufacturing. The outcome for Rivian could influence future investment trends in emerging technologies, emphasizing the need for a robust business model that can withstand initial losses and eventually deliver consistent profits.