


What's Happening?
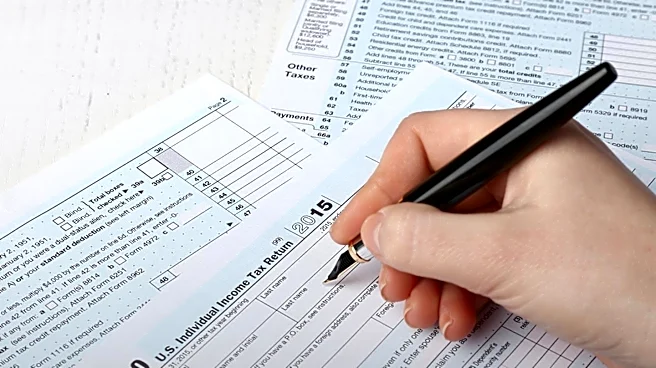
The IRS has clarified that Form 5498, which reports IRA contributions, rollovers, conversions, and year-end fair market value, is an informational return for taxpayers' records and is not directly entered or attached to Form 1040. Instead, the underlying
IRA transactions documented by Form 5498 are reported on specific schedules or forms, such as Schedule 1 for deductible traditional IRA contributions, Form 8606 for nondeductible contributions and Roth conversions, and Form 1040 for IRA distributions. Custodians typically provide fair market value information by January 31 and contribution details by May 31, with the latter date accommodating prior-year contributions made up to the April filing deadline. Taxpayers are advised to file their returns using their own records and only amend if Form 5498 reveals an error. The IRS recommends retaining Forms 8606, 5498, 1099-R, and tax returns until all distributions are made.
Why It's Important?
This clarification is crucial for U.S. taxpayers to accurately navigate their tax obligations related to Individual Retirement Accounts (IRAs). Misunderstanding the role of Form 5498 can lead to common errors, such as mistakenly reporting it as income or incorrectly handling rollovers and conversions, which could result in penalties or incorrect tax liabilities. For instance, a deductible traditional IRA contribution goes on Schedule 1, line 20, while a nondeductible contribution requires Form 8606, Part I. The distinction between these forms and their proper reporting ensures compliance with tax laws and helps taxpayers avoid issues during IRS reviews. The guidance also highlights the importance of meticulous record-keeping, as taxpayers may receive Form 5498 after filing their returns, necessitating a comparison with their own records to ensure accuracy.
What's Next?
Taxpayers should continue to use their personal records to prepare their tax returns, especially if Form 5498 arrives after the filing deadline. If discrepancies are found between their records and the received Form 5498, they should seek tax advice and consider filing an amended return (Form 1040-X) if necessary. Financial institutions and custodians will continue to file Form 5498 with the IRS and provide copies to taxpayers, who should use these forms to reconcile their own records. The IRS will likely continue to emphasize the importance of understanding the specific reporting requirements for various IRA transactions to ensure accurate tax filings and prevent common mistakes.
Beyond the Headlines
The complexity surrounding Form 5498 underscores a broader challenge in tax compliance: the need for taxpayers to understand the nuances of informational returns versus those requiring direct entry on Form 1040. This distinction is vital for managing retirement savings effectively, as incorrect reporting can impact long-term financial planning and tax efficiency. The emphasis on personal record-keeping also highlights the individual responsibility in tax matters, even with forms provided by financial institutions. This situation can be particularly challenging for individuals with multiple custodians, inherited IRAs, or those engaging in Roth conversions, where the potential for error increases. The IRS's guidance aims to empower taxpayers with the knowledge to correctly manage their retirement accounts and avoid unnecessary tax complications.