



What's Happening?
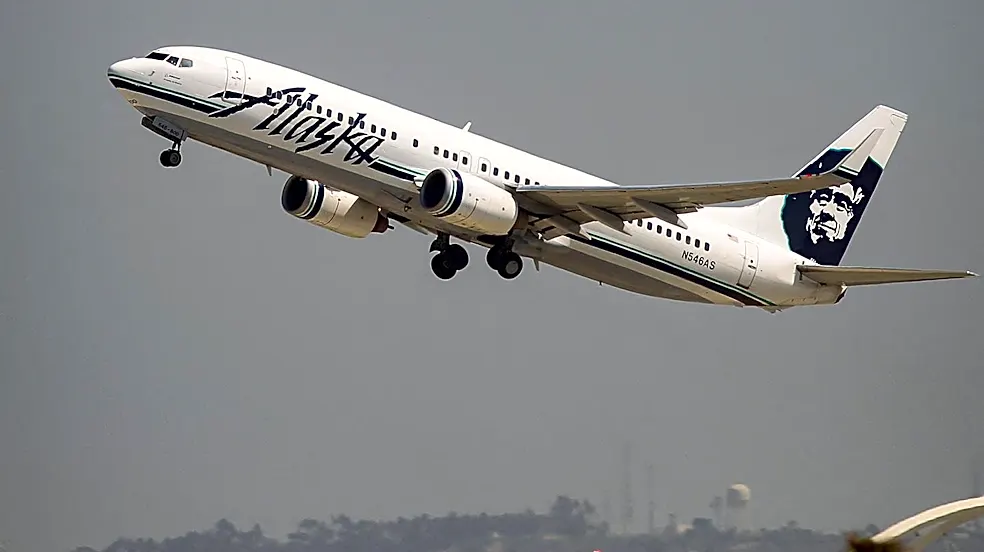
Alaska Air Group reported a third-quarter GAAP net loss of $147 million, or $1.32 per share, primarily due to elevated fuel costs. Despite this, the company saw a 14% year-over-year increase in total revenue, reaching $4.3 billion, with capacity growing
by 2.4%. Unit revenue also increased by nearly 12%, supported by a 13.4% rise in yield. Excluding special items and a revised tax rate, the adjusted net income was $40 million, or $0.36 per share. President and CEO Ben Minicucci noted that demand remains healthy and revenue performed as expected, but fuel costs are anticipated to add $1.8 billion in expenses for the full year. The average fuel price for the third quarter was $3.94 per gallon, exceeding the July expectation of $3.75 per gallon, and is projected to be between $4.65 and $4.85 per gallon for the fourth quarter.
Why It's Important?
The financial performance of Alaska Air Group, a major U.S. airline holding company, reflects the significant impact of fluctuating fuel prices on the airline industry. The reported GAAP net loss, despite strong revenue growth and healthy demand, underscores the vulnerability of airline profitability to external factors like energy costs. This situation highlights a broader challenge for the transportation sector, where operational expenses can quickly erode gains from increased passenger traffic and yield improvements. The company's focus on restoring balance-sheet strength and its long-term growth initiatives, such as expanding premium offerings and international routes, are crucial for its future resilience. However, the immediate pressure from fuel costs indicates potential headwinds for the industry, affecting investment decisions, operational strategies, and ultimately, ticket prices for consumers.
What's Next?
Alaska Air Group anticipates a challenging fourth quarter, forecasting an adjusted loss of between $2.50 and $2.00 per share, and a full-year adjusted loss of $5.50 to $5.00 per share. This outlook is largely driven by the expected additional fuel expense of $650 million in the fourth quarter alone. The company plans to take delivery of 22 Boeing 737-10 aircraft starting late in the first quarter of next year, with some featuring lie-flat seats by 2028. Management expects core earnings to improve by at least $3 to $4 next year, excluding fuel impacts, driven by premium products, loyalty programs, cargo, international service, and network investments. Alaska also intends to file with the U.S. Department of Transportation in the fourth quarter to join Atlantic and Pacific joint international businesses, aiming to strengthen its international economics through partner distribution and capacity coordination.
Beyond the Headlines
The ongoing struggle of Alaska Air Group with elevated fuel costs, despite robust demand and revenue growth, points to a critical structural issue within the airline industry: the delicate balance between operational efficiency and external market volatility. While the company is actively pursuing strategies to diversify revenue streams through premium services, loyalty programs, and international expansion, these efforts are currently being overshadowed by the immediate financial burden of fuel. This situation could accelerate the industry's push towards more fuel-efficient aircraft and alternative energy sources in the long term. Furthermore, the company's plans to join international joint businesses could reshape competitive landscapes in key global markets, potentially leading to increased consolidation or strategic alliances among airlines to mitigate risks and enhance profitability. The emphasis on restoring balance-sheet strength also suggests a cautious approach to capital allocation in an unpredictable economic environment.