

What's Happening?
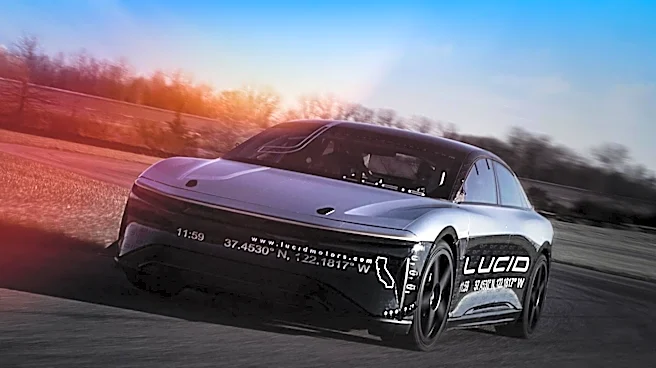
Lucid Group, Inc. (NASDAQ:LCID) experienced a 6.2% drop in its stock price on Thursday, trading as low as $3.19 and closing at $3.20. This decline occurred on a trading volume of 9,293,318 shares, a 30% decrease from its average daily volume. The company,
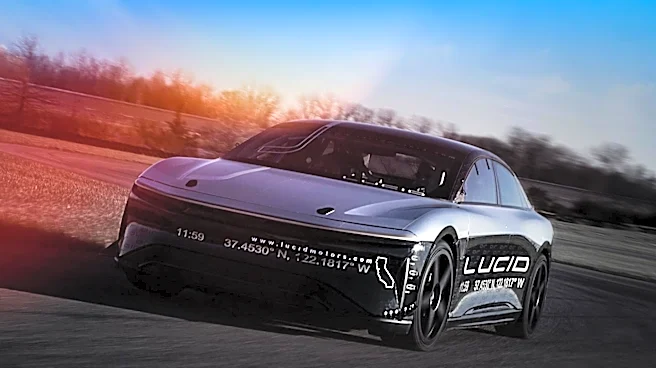
headquartered in Newark, California, designs and manufactures premium electric vehicles, including the Lucid Air sedan and Lucid Gravity SUV. Several brokerage firms have recently adjusted their outlooks on Lucid Group; Citigroup cut its price objective from $14.00 to $11.00, while Morgan Stanley reduced its target from $5.00 to $3.00, assigning an "underweight" rating. UBS Group reiterated a "hold" rating, and William Blair downgraded the stock to "market perform." The company also reported a quarterly EPS of ($2.78), missing the consensus estimate of ($2.36).
Why It's Important?
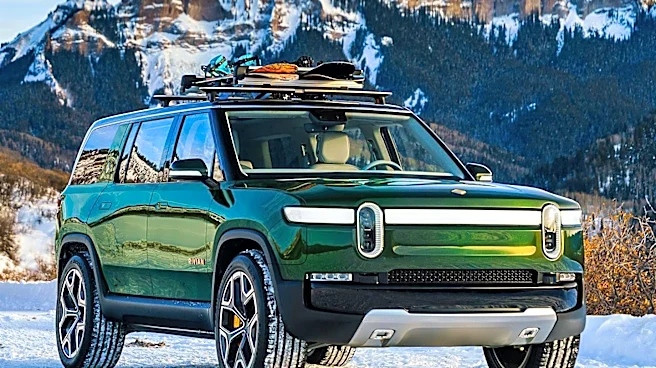
The significant drop in Lucid Group's stock price and the negative adjustments from analysts highlight growing concerns about the company's financial health and market position. The missed earnings per share and negative net margin of 249.21% indicate substantial operational challenges. Increased short interest, which reached 72.62% of the float by October 15th, suggests that a large number of investors anticipate further price declines. This situation is critical for existing shareholders, who face potential dilution if the company seeks new financing to cover its costs. The premium pricing of Lucid's vehicles, coupled with weaker-than-expected deliveries, narrows its buyer pool and intensifies competition from established luxury brands and other EV manufacturers like Tesla and Rivian. The company's capital-intensive business model requires a credible path to profitability, which remains uncertain given its current financial performance.
What's Next?
Lucid Group faces the immediate challenge of demonstrating a clear strategy to improve its financial performance and achieve profitability. The company has emphasized production alignment, cost cutting, and cash flow improvements, which are crucial for its long-term viability. However, a recent 'operating reset' to reduce inventory by building fewer cars than delivered, while lowering carrying costs, also means lower revenue recognition and potentially higher per-vehicle costs due to reduced factory utilization. The company's ability to secure new financing without significantly diluting existing shareholders will be a key factor to watch. Furthermore, the broader economic environment, including interest rates and federal tax credit rules for EVs, will continue to influence consumer demand for expensive electric vehicles, directly impacting Lucid's sales and revenue prospects.
Beyond the Headlines
The challenges faced by Lucid Group extend beyond immediate financial metrics, touching upon the broader competitive landscape and evolving consumer preferences in the electric vehicle market. While Lucid's vehicles are praised for their efficiency, range, and advanced technology, the company operates in a segment increasingly crowded by both EV specialists and traditional automakers. The shift in consumer interest towards hybrids, as observed with brands like Toyota and Honda, also poses a threat to pure battery electric vehicle manufacturers like Lucid. The company's emphasis on over-the-air software updates to enhance vehicle value is a strategic move, but the capital-intensive nature of EV manufacturing, coupled with global supply chain issues and trade tensions affecting battery materials, presents ongoing hurdles. The high short interest also reflects a market sentiment that questions the company's ability to overcome these systemic challenges and achieve sustainable growth.