


What's Happening?
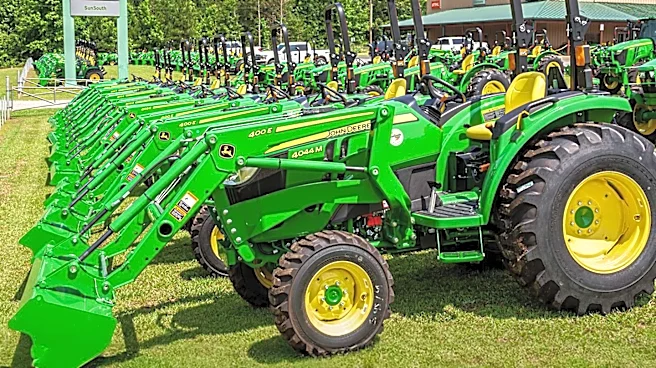
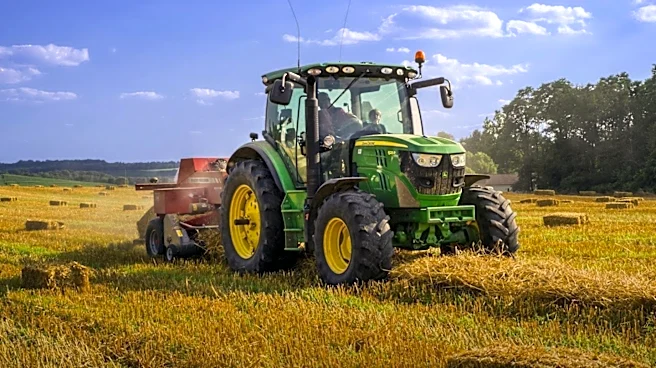
John Deere, a prominent manufacturer of agricultural equipment, has initiated a restructuring plan involving the closure of two U.S. plants and the relocation of several production lines. The facilities affected are in Ottumwa and Clarion, both located
in Iowa. This strategic move aims to consolidate manufacturing operations and enhance operational efficiency by aligning production with available capacity and evolving agricultural equipment demand. The restructuring, which will extend through fiscal 2029, includes transferring the production of forage equipment, self-propelled sprayers, planters, and sugarcane harvesters. Specifically, windrower production from Ottumwa will move to Des Moines Works in Ankeny, Iowa, by fiscal 2027, followed by round baler manufacturing in fiscal 2028, leading to the closure of the Ottumwa plant. Hagie STS self-propelled sprayer production from Clarion will transfer to Thibodaux, Louisiana, starting fiscal 2028, with operations at Clarion ceasing by fiscal 2029. Additionally, small planter manufacturing will relocate from Moline, Illinois, to Paton, Iowa, in fiscal 2027. A notable international shift involves moving U.S. sugarcane harvester production to John Deere's facility in Catalão, Brazil, by fiscal 2029, to consolidate manufacturing where demand is concentrated.
Why It's Important?
This restructuring by John Deere carries significant implications for the U.S. manufacturing sector and the agricultural equipment industry. The closure of the Ottumwa and Clarion plants will result in job losses in those communities, impacting local economies that have historically relied on these manufacturing operations. The consolidation of production lines, while intended to improve efficiency and reduce fragmentation for John Deere, reflects a broader trend of companies optimizing their global supply chains and manufacturing footprints. The relocation of sugarcane harvester production to Brazil highlights how global demand patterns influence domestic manufacturing decisions, potentially reducing the U.S. share in certain specialized agricultural equipment production. For the remaining U.S. facilities receiving transferred production, there could be opportunities for increased investment and job creation, but the net effect on U.S. employment in the sector remains to be seen. This move underscores the competitive pressures and strategic adjustments major industrial players are making to maintain profitability and market leadership in a dynamic global environment.
What's Next?
The restructuring plan will unfold in stages, with production transfers and plant closures scheduled through fiscal 2029. John Deere will manage the transition of windrower production to Des Moines Works by fiscal 2027, followed by round baler manufacturing in fiscal 2028, after which the Ottumwa facility will close. The transfer of Hagie sprayer production to Thibodaux will commence in fiscal 2028, with the Clarion plant ceasing operations by fiscal 2029. The relocation of small planter manufacturing to Paton, Iowa, is set for fiscal 2027. The international transfer of sugarcane harvester production to Brazil is slated for fiscal 2029. During this period, affected employees at the Ottumwa and Clarion plants will face job transitions, and John Deere will likely provide support or severance packages as part of the phased closures. The company will also focus on integrating the relocated production lines into existing facilities to ensure a smooth transition and maintain production continuity for its customers.
Beyond the Headlines
The John Deere restructuring plan extends beyond immediate operational adjustments, signaling deeper shifts in the agricultural machinery industry and the U.S. manufacturing landscape. The decision to consolidate manufacturing and relocate certain product lines, particularly the move of sugarcane harvester production to Brazil, reflects a strategic adaptation to global market dynamics and regional demand concentrations. This could lead to a more specialized manufacturing base within the U.S., focusing on equipment with strong domestic demand, while other production moves to areas with higher local market relevance or lower operational costs. The emphasis on improving operational efficiency and utilizing available capacity suggests a drive towards lean manufacturing principles and potentially increased automation in the remaining U.S. facilities. This long-term strategy could influence future investment decisions in U.S. manufacturing, potentially favoring highly automated and specialized production over labor-intensive processes, thereby reshaping the skill requirements for the workforce in the sector.