


What's Happening?
Wall Street's efforts in tokenization and stablecoins are proceeding under the existing regulatory frameworks of the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) in 2026. This continuity persists despite
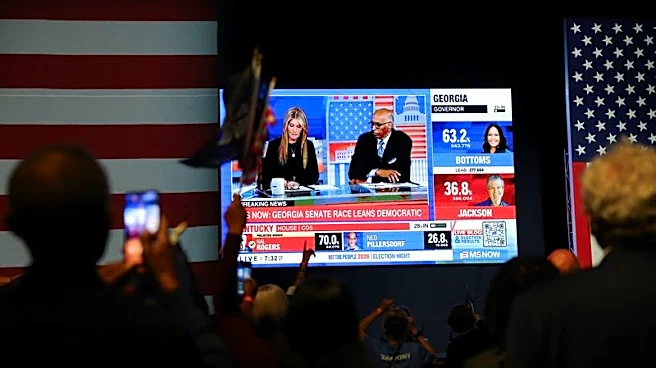
a Democratic sweep in the 2026 elections, which has introduced uncertainty into broader crypto rulemaking. The distinction lies in bank-issued digital assets, such as tokenized securities and dollar-pegged stablecoins, which already operate within established rules. In contrast, market-structure legislation and new digital-asset regimes remain unresolved. The SEC and CFTC have not issued new tokenization-specific rules or enforcement actions that would halt bank-led pilots following the election. This means that tokenized money-market funds, tokenized Treasuries, and dollar-backed stablecoins can continue under the same registration, custody, and disclosure obligations that were in place before the political shift.
Why It's Important?
The continuation of tokenization and stablecoin initiatives under existing rules provides a degree of stability and predictability for Wall Street institutions. These firms have built compliance programs around current regulations, and the absence of immediate changes allows them to proceed with their digital asset strategies without disruption. This regulatory clarity for bank-issued digital assets contrasts sharply with the broader crypto industry, which faces significant uncertainty regarding future regulations. The distinction highlights a bifurcated regulatory approach, where established financial institutions engaging with digital assets are treated differently from the wider, often less regulated, crypto market. This could accelerate the adoption of tokenized assets within traditional finance, as banks can leverage existing legal frameworks to innovate, potentially leading to more efficient capital markets and new financial products.
What's Next?
While tokenization and stablecoin efforts can continue under current rules, the long-term regulatory landscape remains uncertain. The Democratic sweep in 2026 could lead to tougher oversight or new interpretations of existing rules by the SEC and CFTC, even without new legislation. Regulators could apply their current authorities more aggressively, potentially increasing compliance costs and slowing adoption. The key open questions include how long the current rules will last, what form tougher oversight might take, and which broader crypto rules will face the most immediate uncertainty. Market participants will be closely watching for any concrete signals from regulatory bodies or legislative drafts that could alter the current environment for bank-issued digital assets or the broader crypto industry.
Beyond the Headlines
The current regulatory environment reflects a cautious integration of digital assets into traditional finance, prioritizing stability and existing compliance structures. This approach could foster a more controlled evolution of the digital asset market, potentially reducing systemic risks associated with unregulated crypto activities. However, it also raises questions about the pace of innovation and whether a more conservative regulatory stance might hinder the full potential of blockchain technology in finance. The distinction between bank-issued digital assets and broader crypto offerings could create a two-tiered financial system, where institutional players benefit from regulatory clarity while smaller, decentralized projects face greater hurdles. This dynamic could shape the future competitive landscape, potentially consolidating power within established financial entities and influencing the direction of digital finance innovation for years to come.