


What's Happening?
OCI Tokuyama Semiconductor Materials Sdn Bhd (OTSM) is actively involved in the semiconductor-grade polysilicon market, a sector characterized by its high concentration among a few major players. OTSM's operational scope includes coordinating import shipments,
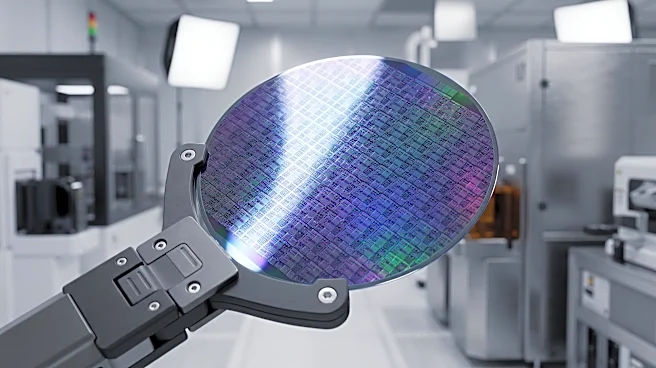
managing customs clearance, and handling import permits and duty/tax exemptions. The company also plays a crucial role in leading Safety, Health & Environment management systems within its manufacturing and chemical plant operations. The broader market for semiconductor-grade polysilicon is dominated by a limited number of companies, including Tokuyama, Wacker Chemie, Hemlock Semiconductor, Mitsubishi Materials, OSAKA Titanium Technologies, OCI, REC Silicon, GCL-Poly Energy, Huanghe Hydropower, and Yichang CSG. These companies maintain their strong positions due to significant capital investments, advanced technological expertise, established customer relationships, and extensive geographical reach. The manufacturing process for polysilicon demands substantial capital, with integrated production facilities requiring billions of dollars in investment, alongside complex chemical processes and years of accumulated technical know-how to achieve high purity levels.
Why It's Important?
The highly concentrated nature of the semiconductor-grade polysilicon market has significant implications for the U.S. semiconductor industry and its supply chain. The reliance on a few dominant global suppliers, including those based in Europe and Asia, means that any disruptions to these key players could have widespread effects on U.S. technology manufacturing. For instance, North America's robust demand from major semiconductor manufacturers is largely met by imports from Europe and Asia, highlighting a potential vulnerability in the domestic supply. The substantial barriers to entry, such as immense capital requirements, complex technological expertise, and the need for long-term contracts and stringent quality certifications, make it difficult for new U.S. companies to enter this critical market. This situation underscores the importance of maintaining stable international trade relations and potentially exploring domestic production incentives to secure a resilient supply of this foundational material for advanced electronics and solar panels.
What's Next?
The semiconductor-grade polysilicon market is expected to continue its concentrated structure in the near term, with existing major players leveraging their established advantages. However, the emergence of Chinese companies, supported by government initiatives, and the development of new technologies could gradually introduce more diversification over the long term. For U.S. semiconductor manufacturers, the immediate future will likely involve continued strategic partnerships with current global suppliers to ensure a stable supply. There may also be increased discussions and policy considerations regarding domestic investment in polysilicon production, potentially driven by national security concerns and the desire to reduce reliance on foreign sources. The ongoing evolution of semiconductor technology and the increasing demand for high-purity materials will further shape the competitive landscape, potentially leading to new collaborations or acquisitions among the leading firms to consolidate market share or expand technological capabilities.
Beyond the Headlines
Beyond the immediate supply chain dynamics, the concentration in the semiconductor-grade polysilicon market raises deeper questions about global technological sovereignty and economic resilience. The U.S. economy, heavily dependent on advanced semiconductors for various industries from defense to consumer electronics, faces strategic challenges when critical raw materials are controlled by a limited number of international entities. This situation could influence future U.S. industrial policy, potentially leading to greater emphasis on reshoring or nearshoring critical manufacturing capabilities. Furthermore, the environmental and safety management systems, which OTSM prioritizes, are becoming increasingly important as global supply chains face greater scrutiny over sustainability and ethical practices. The long-term implications could include a push for more environmentally friendly production methods and stricter regulatory oversight across the entire semiconductor material supply chain, impacting both established players and potential new entrants.