
What's Happening?
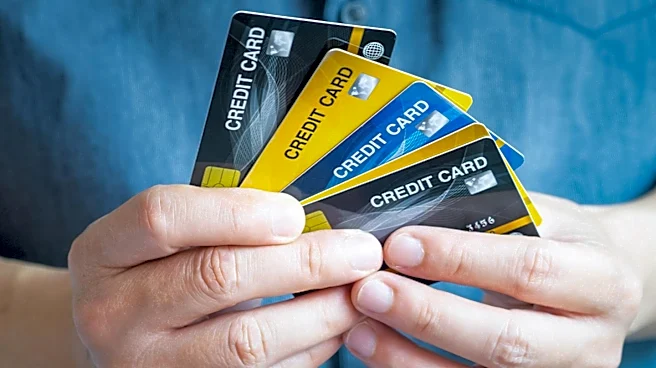
Credit cards are presented as valuable financial tools that offer more than just a means of payment. They provide convenience, robust fraud protection, rewards programs, and a crucial opportunity to build credit history. Unlike debit cards, which draw
directly from a bank account, credit cards offer a line of credit, allowing users to review and dispute unauthorized charges before payment is due, thus safeguarding bank account funds. Experts recommend using credit cards for online purchases due to superior fraud protection. The ideal use involves making planned purchases and paying the balance in full each month to avoid interest charges while still benefiting from rewards and protections. Understanding interest rates and repayment terms is essential to grasp the true cost of purchases, especially when balances are carried over multiple months. Credit cards can also serve as a safety net for unexpected expenses, provided there's a plan for prompt repayment.
Why It's Important?
The strategic use of credit cards is vital for consumers seeking to manage their finances effectively and build a strong financial foundation. By offering fraud protection and a mechanism for building credit, credit cards can significantly enhance financial security and future opportunities, such as securing loans for homes or cars. Misunderstanding or misusing credit cards, however, can lead to accumulating debt and high-interest charges, undermining financial stability. Therefore, educating consumers on responsible credit card usage—focusing on planned spending, full monthly payments, and understanding terms—is crucial. This approach empowers individuals to leverage the benefits of credit cards while mitigating risks, contributing to overall economic health and individual financial well-being.
What's Next?
As consumers increasingly rely on digital transactions, the role of credit cards as secure payment instruments will likely expand. Financial institutions are expected to continue innovating with reward programs, fraud prevention technologies, and user-friendly tools to help cardholders manage their accounts. There will likely be an ongoing emphasis on financial literacy initiatives to educate the public on the responsible use of credit cards, focusing on budgeting, understanding interest rates, and the importance of timely payments. The development of more personalized credit card offerings tailored to individual spending habits and financial goals could also become more prevalent. Furthermore, the integration of credit cards with digital wallets and mobile payment systems will continue to evolve, offering greater convenience and security in everyday transactions.
Beyond the Headlines
The discussion around credit cards extends beyond their immediate financial utility to broader implications for consumer behavior and economic empowerment. The ability to build a credit history through responsible use is a cornerstone of financial independence, enabling access to various financial products and services. Conversely, the ease of access to credit can also lead to overspending and debt, highlighting the psychological aspects of consumer finance. The ongoing evolution of credit card features, such as enhanced fraud protection and rewards, reflects a dynamic interplay between technological advancements, market competition, and consumer demand for security and value. This continuous adaptation underscores the credit card's enduring role as a central component of the modern financial ecosystem, shaping how individuals manage their money and interact with the economy.