


What's Happening?
PIMCO, a global leader in active fixed income, is facing estimated losses exceeding $35 million from its investment in the Commercial Mortgage-Backed Securities (CMBS) deal backed by Philadelphia's Centre Square office complex. A judge recently approved
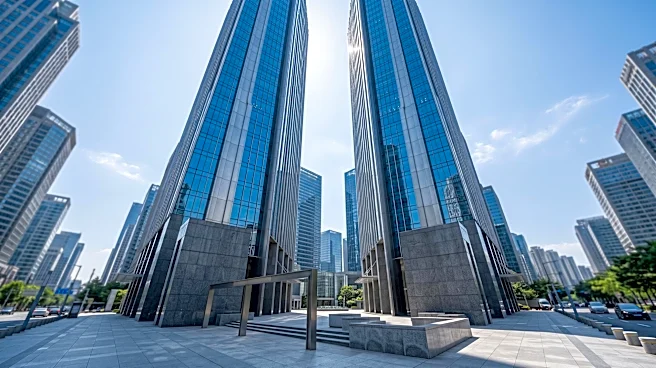
the sale of the two-tower property for $70 million, a substantial decrease from its 2019 appraisal of $471 million. This drastic reduction in value means that even top-rated AAA securities within the CMBS are expected to incur losses, a rare occurrence since the 2008 financial crisis. PIMCO holds approximately $58 million in face value across the $368 million deal, with about half of that in the top-rated portion. The Centre Square complex, located across from Philadelphia City Hall, saw its occupancy plummet to 28% by June, leading to the mortgage being transferred to a workout specialist and eventual foreclosure. The buyers of the property plan to convert parts of the complex into a luxury hotel and apartments, reducing the office space.
Why It's Important?
This situation highlights the growing distress within the U.S. commercial real estate market, particularly for older office assets. The significant loss on a AAA-rated CMBS tranche is a stark indicator of the severity of the downturn, marking only the third such instance since the financial crisis. For PIMCO, a major institutional investor, these losses underscore the risks associated with exposure to troubled office properties. The Centre Square deal is a single-asset, single-borrower (SASB) structure, which concentrates risk and magnifies the impact of a single property's failure. This event could prompt other investors and financial institutions to re-evaluate their exposure to similar CMBS deals, potentially leading to increased scrutiny and devaluations of other office-backed securities. The planned conversion of the Centre Square complex also reflects a broader trend of repurposing underperforming office spaces, which could reshape urban landscapes and property values in major U.S. cities.
What's Next?
The sale of the Centre Square complex is expected to finalize in the coming weeks, after which proceeds will be distributed to creditors. This workout serves as a precedent for other distressed office loans, with many more expected to reach similar decision points as their maturities approach. Wall Street strategists anticipate a recovery of approximately 44 cents on the dollar for the Centre Square CMBS, which will wipe out seven lower-ranking debt tranches. Markets like Chicago, downtown Los Angeles, Portland, and Denver are identified as areas where office values have not fully recovered, suggesting that investors in these regions may face similar losses. The ongoing transformation of office spaces, driven by changing work patterns and declining demand, will likely continue, leading to more conversions and redevelopments in urban centers across the U.S.
Beyond the Headlines
The Centre Square CMBS loss extends beyond immediate financial implications, revealing deeper structural shifts in the U.S. economy and urban planning. The dramatic decline in office occupancy, exacerbated by the pandemic, has fundamentally altered the demand for traditional office spaces. This event underscores the vulnerability of financial products, like SASB CMBS, that are heavily reliant on the performance of a single asset. The repurposing of office buildings into residential or hospitality spaces, as planned for Centre Square, signifies a broader urban revitalization trend, but also poses challenges for municipal tax bases that have historically relied on commercial property values. This situation could accelerate discussions around adaptive reuse policies, zoning reforms, and incentives for developers to transform underutilized commercial real estate, ultimately reshaping the economic and social fabric of U.S. cities.