
What's Happening?
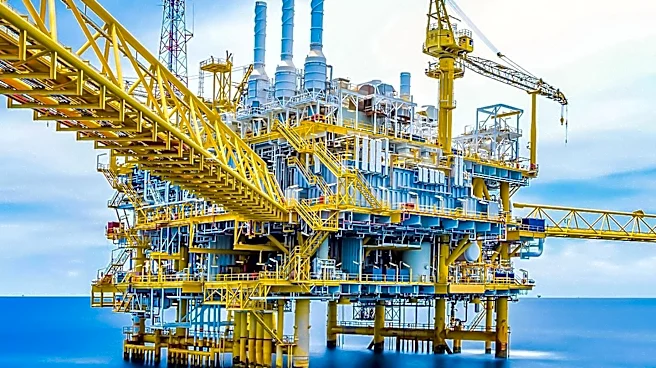
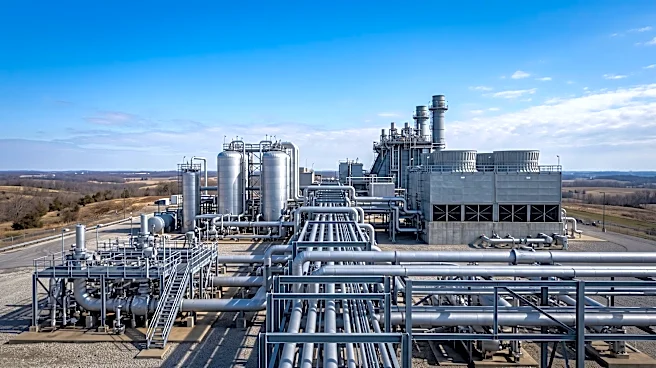
Mexico's oil and gas infrastructure market is forecast to reach $11.5 billion by 2035, representing a 24.9% share of Latin America's total oil and gas infrastructure revenue. This growth is driven by several key factors within the country. Upstream field
development, which involves the exploration and production of crude oil and natural gas, is a significant contributor. Additionally, ongoing refinery modernization projects aim to enhance the efficiency and capacity of Mexico's oil processing facilities. The expansion and upgrade of gas transmission networks are also crucial, as they facilitate the movement of natural gas across the country. Furthermore, Mexico's emerging ambitions in the Liquefied Natural Gas (LNG) sector, including potential export capabilities, are expected to underpin the domestic project pipeline. These combined efforts indicate a robust investment landscape in Mexico's energy sector infrastructure over the next decade, positioning it as a key player in the regional market.
Why It's Important?
The projected growth in Mexico's oil and gas infrastructure market holds significant importance for both its domestic economy and regional energy dynamics. For Mexico, increased investment in upstream development, refinery modernization, and gas networks can lead to enhanced energy independence, job creation, and economic diversification. A more robust energy infrastructure can also attract foreign direct investment, as international companies seek to participate in these expanding opportunities. Regionally, Mexico's strengthened energy sector could influence supply chains and energy security across Latin America. As Mexico develops its LNG capabilities, it could become a more prominent exporter, impacting global energy markets. The modernization of refineries could also lead to a more stable supply of refined products, potentially reducing reliance on imports. This growth signifies a strategic push by Mexico to solidify its position as a major energy producer and refiner in the Americas.
What's Next?
Looking ahead, Mexico is expected to continue prioritizing investments in its upstream oil and gas sector, with a focus on developing new fields and optimizing existing ones. The modernization of its refining capacity will likely proceed, aiming to improve efficiency and reduce the production of lower-value fuels. Further expansion of gas transmission and distribution networks is anticipated to meet growing domestic demand and support potential LNG export facilities. Key stakeholders, including the Mexican government, state-owned oil company Pemex, and international energy firms, will play crucial roles in these developments. We can expect continued tenders for infrastructure projects, partnerships between public and private entities, and policy adjustments designed to attract and facilitate investment in the energy sector. The success of these initiatives will depend on stable regulatory frameworks and sustained capital expenditure.
Beyond the Headlines
The expansion of Mexico's oil and gas infrastructure carries broader implications beyond immediate economic gains. Environmentally, increased fossil fuel extraction and processing raise concerns about carbon emissions and the country's commitment to climate goals. There will be a critical balance to strike between energy security and environmental sustainability. Socially, large-scale infrastructure projects can lead to both opportunities and challenges for local communities, including land use issues, potential displacement, and the need for robust social impact assessments. Geopolitically, Mexico's growing energy capabilities could alter its standing in North American energy discussions, potentially increasing its leverage in trade and energy policy dialogues with the United States and Canada. The long-term shift could see Mexico becoming a more self-sufficient and influential energy player, but this path will require careful navigation of environmental, social, and political complexities.